Capitalize on today's evolving market dynamics.
With changes to taxes and interest rates, it's a good time to meet with a wealth advisor.

The U.S. dollar weakened in 2025 and strengthened in 2026, changing U.S. investors’ returns on international holdings after currency conversion.
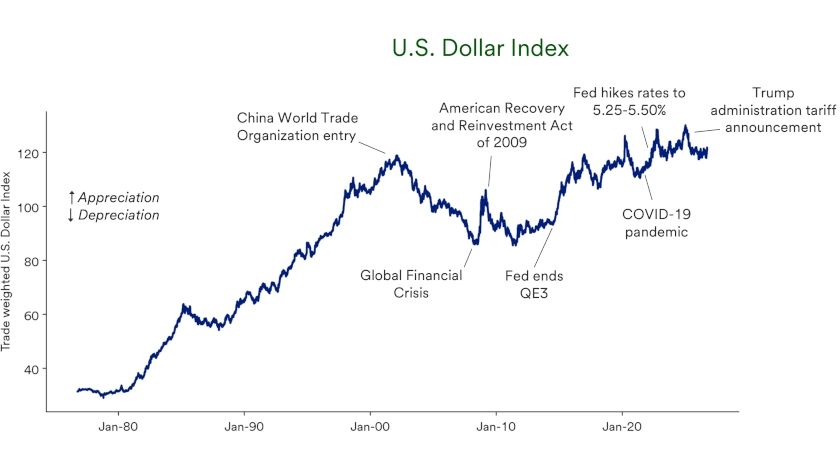
Interest-rate expectations, global investment demand, trade flows, and inflation shape dollar strength, while the U.S. Dollar Index tracks the currency against major peers.
Currency fluctuations affect import prices, corporate earnings and overseas investments, but a diversified portfolio reduces the need to react to short-term U.S. dollar moves.
Recent U.S. dollar swings alter returns for globally invested portfolios. The U.S. Dollar Index, or DXY, compares the dollar with a basket of major currencies; it fell 9.4% in 2025, then rose 4.3% in 2026 through October 12. 1 A weaker dollar increased the value of overseas returns after conversion into dollars in 2025, while the 2026 rebound created a partial headwind.
Headline currency moves can appear more consequential than their long-term portfolio effect. Investors cannot control daily exchange rates, yet they can decide how much they hold in U.S. and international markets, how broadly they diversify and how long they remain invested. Understanding the dollar’s role in global finance helps investors make those decisions without trying to forecast its next short-term move.
The U.S. dollar serves as the world’s primary reserve currency and a common unit for international trade, borrowing and payments. Central banks hold dollars as reserves, many commodities such as oil and gold trade in dollars, and companies frequently use the currency to settle transactions across borders. Global borrowers also issue substantial amounts of dollar-denominated debt, which creates ongoing demand for dollars to make interest and principal payments.
This broad use sustains demand for the dollar beyond any single economic report or Federal Reserve decision. Deep U.S. financial markets allow investors to buy and sell Treasury securities, stocks, corporate bonds, and other assets at scale. The dollar also benefits from an established global network of reserves, contracts and financing arrangements that institutions cannot quickly replace.
Currency values reflect the global flow of money through trade and investment. Investors compare interest rates, economic growth, inflation and financial-market stability across countries, then direct capital toward the combination they find most attractive. “Relative currency values reflect global capital flows,” says Rob Haworth, senior investment strategy director with U.S. Bank Asset Management Group. “When the dollar strengthens, more foreign money is generally moving into U.S. assets than U.S. money is moving abroad. Those flows can change as investors reassess growth, inflation and policy in the United States relative to other countries.”
“When the dollar strengthens, more foreign money is generally moving into U.S. assets than U.S. money is moving abroad. Those flows can change as investors reassess growth, inflation and policy in the United States relative to other countries.”
Rob Haworth, senior investment strategy director with U.S. Bank Asset Management Group
Four forces drive most changes in the dollar: interest-rate differences, global investment demand, trade flows and inflation expectations. Higher U.S. interest rates can attract foreign capital when investors believe the added income compensates for inflation, market volatility and potential currency losses, especially when U.S. rates exceed foreign rates after accounting for inflation. Strong economic growth and confidence in U.S. markets can also draw investment, while persistently higher inflation can erode purchasing power and weaken a currency over time.
The dollar weakened in 2025 as central banks broadly eased monetary policy and investors expected additional Federal Reserve rate cuts. President Donald Trump's tariff announcements also raised questions about U.S. inflation and growth, reducing the relative appeal of some dollar-based assets. The currency later stabilized as incoming economic data changed those expectations.
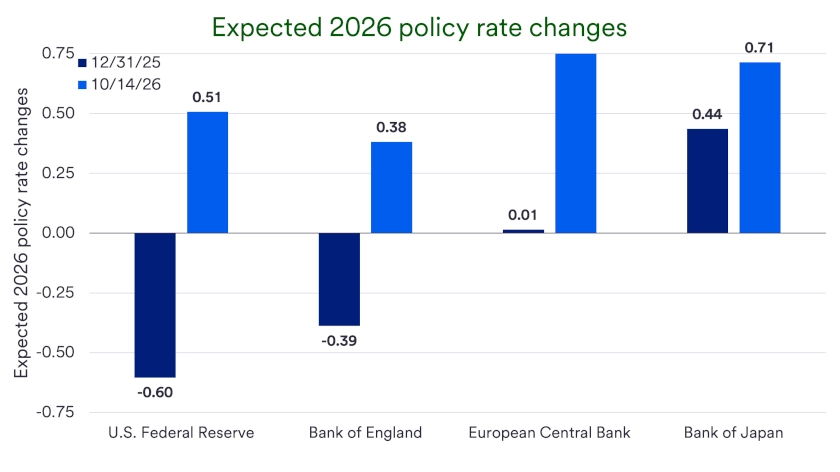
The policy backdrop reversed in 2026 as higher oil prices added to inflation and pushed expected interest rates higher. On September 16, the Federal Open Market Committee raised the federal funds target range by 0.25 percentage point to 3.75%–4.00%, its first increase in more than three years. The Fed emphasized returning inflation to its 2% target while employment and consumer spending remained resilient, and markets expected another increase in 2026 after the meeting.
For the dollar, the direction of interest rates matters less than how the U.S. outlook changes relative to other countries. Several major central banks also raised rates or appeared likely to do so in 2026, limiting the dollar’s advantage from higher U.S. rates alone. The dollar strengthened when investors revised the expected U.S. policy path upward by more than comparable expectations abroad, drawing additional capital toward dollar-based assets.
A stronger dollar can lower the U.S. price of imported goods. A European car priced at €50,000 costs $60,000 when one euro buys $1.20, but $45,000 when one euro buys $0.90, even though its euro price never changes. The exchange rate, rather than the manufacturer’s sticker price, produces the difference for the U.S. buyer.
Currency changes affect household budgets differently because imported necessities account for varying shares of spending. A weaker dollar can raise the cost of imported food, fuel and other goods, putting more pressure on consumers who spend a larger share of income on such necessities. A stronger dollar can reduce import costs, while households with larger investment portfolios may notice more of the effect through the dollar value of their international holdings.
A stronger dollar can reduce the reported revenue and export competitiveness of U.S. companies that sell overseas. Converting foreign revenue into a stronger dollar reduces the amount reported in dollars, and a stronger currency can make U.S. exports more expensive for overseas customers. “Continued dollar strength could restrain reported corporate earnings and stock returns in the short term,” Haworth says. “Investors should assess currency alongside sales growth, profit margins, valuations and economic conditions rather than use the exchange rate as a stand-alone market signal.”
Large federal deficits may raise the government’s borrowing costs over time as the Treasury issues more debt and devotes more revenue to interest payments. Total gross federal debt reached $40.3 trillion on October 5, 2026, and the 10-year Treasury yield rose from 4.17% at the start of the year to 5.24% on October 12. 1, 2 The 10-year yield represents the market interest rate for lending to the federal government for a decade. Economic growth, inflation, expected Federal Reserve policy and debt supply all influence the rate.
Economic growth, inflation and changing policy-rate expectations explain most of the 2026 rise in developed-market 10-year government bond yields. U.S. Bank Asset Management Group research attributes a smaller share to fiscal concerns and heavy bond issuance. The difference between 30-year and 10-year Treasury yields, another gauge investors use to assess longer-term fiscal risk, remained near its historical average through September, indicating that investors had not demanded an unusually large premium for longer-term fiscal risk. 1
The size of the U.S. economy and the depth of its financial markets continue to attract global capital despite fiscal concerns. A large, diverse economy generates income for companies and investable assets, while deep capital markets make it easier for global investors to hold and trade dollar-based securities. The International Monetary Fund reports the dollar represents 56.7% of allocated global foreign-exchange reserves in the second quarter of 2026, down slightly from 57.2% in the first quarter but still the largest share held in any currency. 3
Currency directly changes the returns U.S. investors receive from assets outside the United States. International holdings produce returns in their local currencies, then those gains or losses translate back into dollars in U.S. investment accounts. In 2025, the MSCI EAFE Index, a benchmark for developed-market stocks outside the United States and Canada, returned 23.7% in local currencies and 31.2% for U.S. investors after a weaker dollar increased the converted return. 1
The effect reversed as the dollar strengthened in 2026. The MSCI EAFE Index returned 12.1% in local currencies through October 12 but 9.0% in U.S. dollars, showing how conversion can reduce a U.S. investor’s result even when overseas markets rise. 1 Over longer periods, currency contributes to total return alongside earnings growth, valuations, interest rates, and economic fundamentals.
Currency movements can raise or lower investment returns, but they rarely determine the long-term outlook on their own. “Currencies generally fluctuate less than stocks, and their direction is difficult to predict because relative values respond to many forces at once,” Haworth says. “Equity investors generally should not change long-term allocations in response to short-term dollar moves. Broad diversification across markets and asset classes can help investors avoid making large allocation changes in response to short-term currency headlines.”
The value of the U.S. dollar changes over time as investors, businesses and governments respond to shifts in economic conditions and confidence. Interest-rate expectations influence the dollar because investors compare potential returns across countries. Higher expected U.S. rates can attract capital and strengthen the dollar when the U.S. outlook rises relative to comparable expectations abroad. Inflation, demand for safe investments and trade flows also shape the currency over longer periods.
The U.S. dollar anchors the global financial system. Countries, companies and banks use it every day to trade goods, borrow money and settle payments across borders, and many key commodities, including oil, are priced in dollars, which sustains steady demand. A large share of global debt is also issued in dollars, especially in emerging markets, so the currency keeps a leading role in world finance.
Long-term currency trends usually reflect the strength and stability of a country’s economy. Steady growth, trusted institutions and confidence in financial markets attract foreign investment and support the dollar over time, and stronger exports add to that support by raising demand for U.S. goods and services. Inflation and interest rates weigh on the trend as well, since persistent inflation erodes a currency, while stable prices and competitive rates help the dollar hold its value.
Currencies move every day, but major shifts usually develop slowly. Investors, businesses and central banks often wait for clearer signs that economic trends will last before making large changes, and long-term trade agreements, loans and other financial commitments limit sudden swings in demand. The foreign exchange market is the largest and most liquid in the world, so it takes sustained pressure to move major currencies, and big changes in the dollar usually build over time.
The practical takeaway is to stay anchored to a diversified approach and discuss any major overseas exposure with your wealth management professional, especially when headlines tempt quick reactions.
The dollar often moves as money flows around the world through trade and investing. Interest-rate differences, demand for investments across countries, trade flows, and inflation expectations can all push the dollar higher or lower.
A strong dollar can lower import costs for U.S. consumers. It can also reduce the dollar value of foreign revenue for U.S. companies and lower overseas investment returns after conversion into dollars. The effect tends to be larger for globally oriented companies and international funds than for investments focused on the domestic economy.
A weak dollar can increase overseas gains after U.S. investors convert them into dollars. It can also raise import costs and add to inflation pressure if businesses pass those costs to consumers. Investors with little foreign exposure may see less direct currency impact, although multinational companies in U.S. indexes can still respond to exchange-rate changes.
In recent years, the communications services and information technology sectors routinely outperformed the broader S&P 500, despite exhibiting some volatility, and this trend is expected to continue in 2026.
We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.

 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.