Capitalize on today’s evolving market dynamics.
With changes to taxes and interest rates, it's a good time to meet with a wealth advisor.
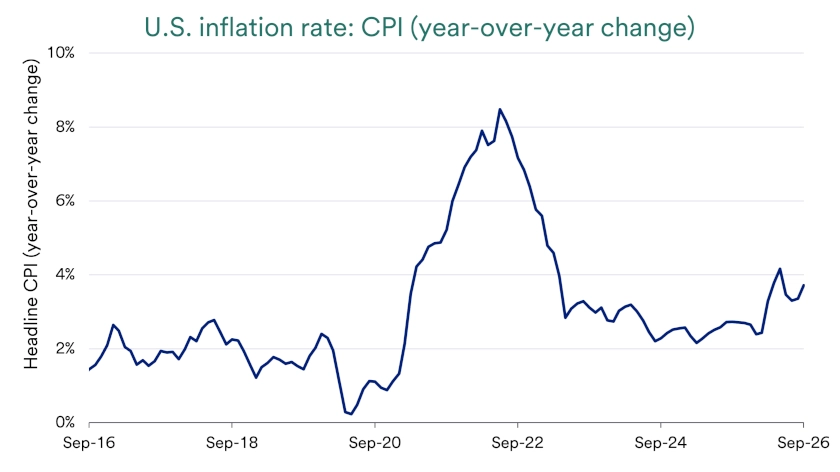
Inflation accelerated in September as gasoline, energy, and shelter costs pushed the Consumer Price Index (CPI) up 3.7% from a year earlier, while core CPI rose 2.6%.
Inflation pressures extend beyond consumer prices, with producer prices rising 6.3% over the past year as businesses faced higher energy, goods, and transportation costs.
Inflation and Federal Reserve policy continue to shape rates and returns, while diversification can reduce reliance on any single outcome as energy, tariffs, demand, and shelter costs change.
Inflation reduces purchasing power, raises business costs, and influences interest rates across the economy. Households lose purchasing power when wages, income, and investment gains fail to keep pace with prices. Businesses must decide whether to absorb higher costs for labor, materials, transportation, and financing or pass them to customers.
The direction of inflation tells only part of the story. Its source and duration help determine how price pressure may affect consumer spending, economic growth, corporate profits, and interest rates. September data show broader pressure from energy, shelter, and business input costs, while underlying consumer inflation remains below the headline rate.
The Consumer Price Index, or CPI, rose 0.6% in September and 3.7% from a year earlier, up from a 3.4% annual rate in August. Gasoline prices jumped 9.1% and accounted for more than half of the monthly increase, while the broader energy category rose 5.2% and shelter increased 0.4%. Food prices held steady, but the energy surge raised costs for households and businesses. 1
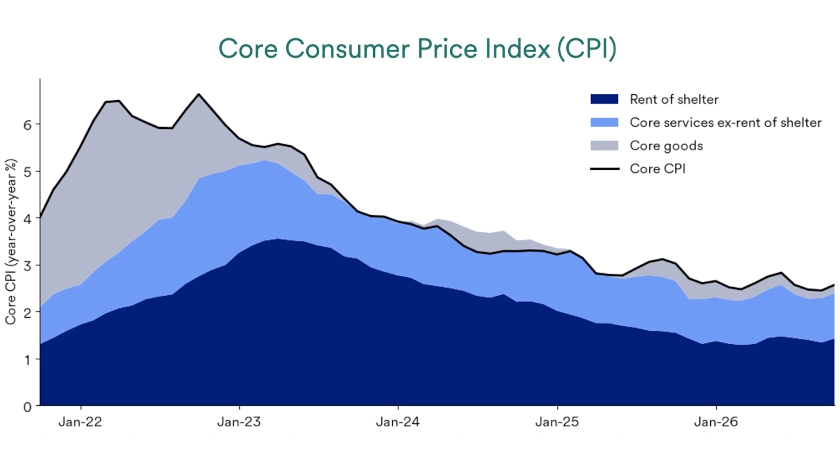
Core CPI excludes food and energy because those prices often move sharply from month to month. Core prices rose 0.3% in September and 2.6% from a year earlier, compared with a 2.4% annual increase in August. The gap between headline and core inflation shows how energy can change the near-term inflation picture even when underlying price pressure moves more gradually. 1
Shelter prices rose 0.4% in September after increasing 0.3% in August, and the index stood 3.2% above its year-earlier level. Official shelter measures often trail current rental conditions because they capture the full stock of leases rather than only newly signed contracts. Slower growth in advertised rents can therefore take time to appear in CPI. 1
Housing also affects inflation through household budgets, construction costs, and interest rates. Earlier rent moderation may reduce shelter inflation as it enters the index, but September’s increase shows an uneven path. Housing typically influences inflation gradually, so one monthly report does not establish a lasting trend.
The Producer Price Index, or PPI, tracks the prices businesses receive for goods and services. Final-demand prices rose 1.3% in September and 6.3% from a year earlier, the largest 12-month increase since December 2022. Prices excluding food, energy, and trade services rose 0.5% for the month and 5.0% over the past year, showing that business inflation extended beyond the energy shock. 2
Energy drove much of the September increase, but transportation, warehousing, and trade-service margins also rose. Final-demand goods prices increased 2.6%, including a 10.8% rise in energy, while services advanced 0.8%. Companies can absorb higher costs, improve productivity, change suppliers, or raise customer prices, so increases in PPI do not flow directly or immediately into CPI. 2
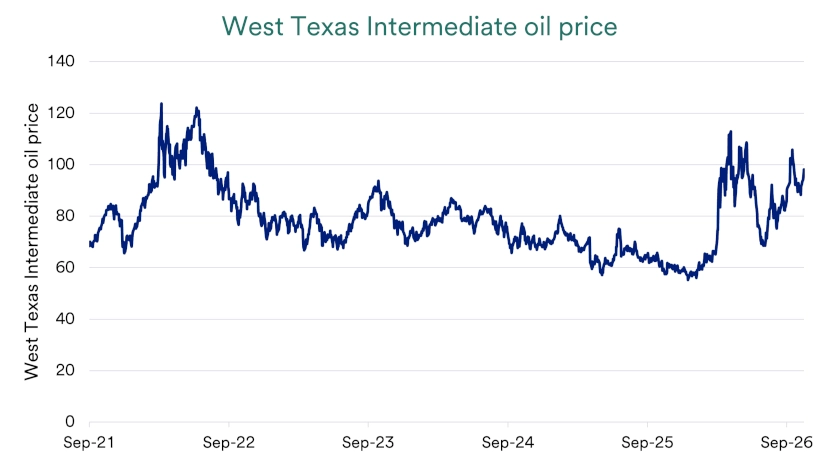
Geopolitical conflict can lift inflation by disrupting energy supplies and raising transportation, shipping, and insurance costs. Consumers see the effects in gasoline and utility bills, while companies pay more to produce and deliver goods. A prolonged energy shock can also slow economic growth because households and businesses spend more on fuel without receiving additional goods or services.
“Markets are sensitive to sustained, accelerating inflation, while inflation excluding energy has remained elevated but comparatively steady,” says Rob Haworth, senior investment strategy director with U.S. Bank Asset Management Group. “Labor markets are also important because meaningful weakness would increase the risk of a sharper economic slowdown.” Taken together, inflation, employment, and growth provide a fuller economic picture than any one report.
“Markets are sensitive to sustained, accelerating inflation, while inflation excluding energy has remained elevated but comparatively steady. Labor markets are also important because meaningful weakness would increase the risk of a sharper economic slowdown.”
Rob Haworth, senior investment strategy director with U.S. Bank Asset Management Group
Tariff policy has moved through several phases rather than settling at one rate. Collections first rose sharply as the effective tariff rate, measured as customs revenue divided by the value of imported goods, climbed from earlier levels. Court decisions then produced refunds for some duties already paid, temporarily pushing net Treasury tariff revenue below zero before collections returned to positive territory.
The effective tariff rate has declined from its earlier high but remains positive, and trade policy has not reached a stable endpoint. The Trump administration has shifted toward other trade authorities and more targeted actions, leaving businesses to make sourcing, inventory, and pricing decisions while applicable costs change quickly. The inflation effect will depend on where the effective rate settles, how long it stays there, and how much of the cost businesses absorb rather than pass to customers.
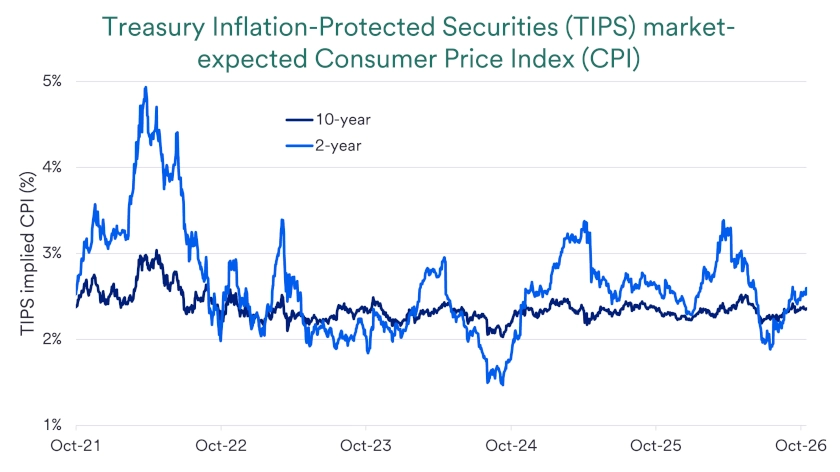
Treasury Inflation-Protected Securities, or TIPS, adjust their principal value with CPI. The difference between TIPS yields and conventional Treasury yields at the same maturity produces the breakeven inflation rate, a market-based estimate of average inflation over that period. A rising breakeven rate signals higher expected inflation, while a falling rate signals lower expectations, although market liquidity and the return investors demand for inflation risk can also affect the measure.
“Capital markets provide a valuable source of information about the inflation outlook because they often incorporate new information faster than lagging economic data or official forecasts,” says Bill Merz, head of capital markets research for U.S. Bank Asset Management Group. The 10-year breakeven inflation rate stood at 2.35% on October 14, meaning market participants expected CPI inflation to average about 2.35% over the next decade. 3 The reading showed concern about the recent energy-driven increase, but not fear of a return of the much higher inflation rates of 2021 and 2022; wages, spending, and Federal Reserve policy provide important additional context.
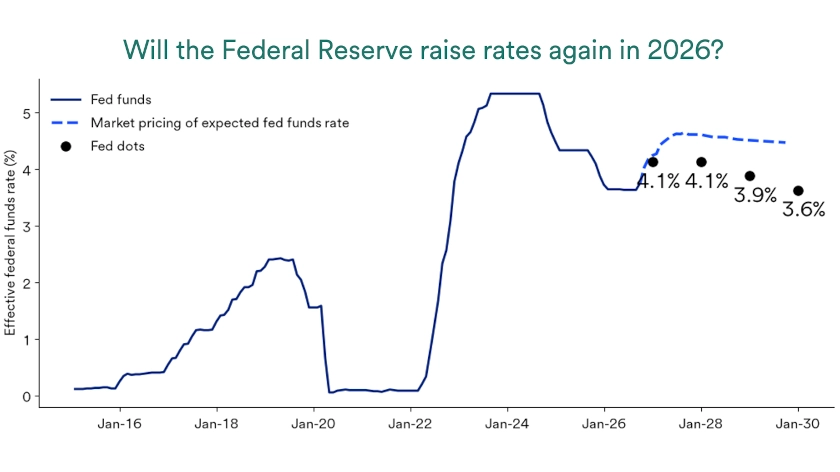
The Federal Reserve raised the federal funds target range to 3.75% to 4.00% at its September meeting, its first increase in three years. The policy rate influences short-term borrowing costs, while longer-term market rates affect mortgages, business financing, and many investment valuations. Stronger September CPI and PPI readings support keeping policy restrictive while policymakers assess whether higher energy and business costs spread into broader inflation. 4
The Fed defines its 2% longer-run inflation goal using the annual change in the headline Personal Consumption Expenditures price index, or PCE, which measures prices across a broad range of consumer spending. August headline PCE rose 3.4% from a year earlier, while core PCE, which excludes food and energy, rose 3.0%. These readings remain above the Fed’s goal but show less inflation than September CPI, which placed more weight on the sharp rise in gasoline prices. 5
Inflation matters to investors because it can reduce the real value of portfolio growth over time. Even when an account balance rises, those gains may buy less if the cost of goods and services continues to increase. For long-term investors, the goal is not only to grow assets, but also to preserve purchasing power.
Inflation can also influence interest rates, which can affect both bonds and stocks. When rates move higher, older bonds with lower yields often lose value in the market. Higher rates can also weigh on stock prices by reducing the present value of future earnings. A diversified investment strategy can help investors manage these risks while staying focused on long-term growth.
Inflation reduces purchasing power by making everyday goods and services more expensive over time. As prices rise, each dollar buys less than it did before. This gradual change can affect household budgets, retirement planning, and long-term savings goals.
The long-term impact can be significant. Based on the Consumer Price Index from the U.S. Bureau of Labor Statistics, something that cost $1 at the start of 2000 cost about $1.93 by the start of 2026. That means prices nearly doubled over that period, showing why inflation remains an important part of financial planning and investment strategy.
Inflation explains the difference between nominal returns and real returns. A nominal return is the number shown on an investment statement, paycheck, or savings account. A real return adjusts for inflation and shows how much buying power increased after rising prices are considered.
For example, a bond may pay a 5% nominal yield over a year. If inflation averages 2% during that same period, the real return is closer to 3%. Investors track this difference because strong long-term results depend on growing wealth faster than the cost of living.
Many people notice inflation when prices jump in a given month or year. Investors usually focus on inflation as a long-term risk because prices tend to rise over time, even when inflation slows for a period. That steady increase can gradually reduce the future value of savings and investment gains.
For long-term investors, inflation is not just a short-term headline. It is an ongoing part of portfolio planning, retirement income planning, and wealth preservation. A sound investment approach aims to outpace inflation over time so investors can maintain spending power and stay on track toward long-term financial goals.
No single monthly figure captures the inflation outlook. Energy prices caused much of September’s acceleration, but firmer shelter costs and a broad increase in producer prices raise the risk that inflation stays elevated. The next signals include whether energy prices stabilize, businesses pass higher costs to customers, shelter inflation eases, and consumer demand remains strong.
A diversified portfolio cannot prevent losses, but it can reduce dependence on a single inflation or interest-rate outcome. Stocks, bonds, and other assets respond differently to changing growth, inflation, and policy conditions, and those relationships can shift over time. Portfolio decisions should reflect long-term objectives rather than a forecast tied to one data release.
The best response to an uncertain inflation path is to focus on the decisions within your control. A disciplined financial plan and broadly diversified portfolio can reduce the temptation to make lasting changes after one report or a short burst of market volatility. Regular rebalancing can keep portfolio risk aligned with long-term goals as markets and interest rates move.
If energy pressure fades and shelter inflation slows, the case for lower interest rates could strengthen. If higher producer costs, tariffs, or firm demand spread into consumer prices, restrictive policy could last longer or rates could rise further. Talk with your financial professional about how your portfolio aligns with your goals, time horizon, and comfort with short-term swings, and discuss whether any adjustments make sense for your situation.
What is the current inflation rate?
In September 2026, CPI rose 0.6% for the month and 3.7% from a year earlier. The annual rate accelerated from August’s 3.4% pace, and core CPI also accelerated from 2.4% to 2.6%. 1 Household experiences can differ from the national average because spending patterns vary and food, energy, and housing prices do not move together.
Why does “core” inflation matter?
Core inflation excludes food and energy because those prices can change sharply from month to month. Core CPI rose 0.3% in September and 2.6% over the prior year, helping investors and policymakers assess broader price pressure trends. 1 The Fed still targets headline PCE inflation but uses core readings to evaluate the underlying trend.
Why does the Fed focus on PCE inflation instead of CPI?
The Fed defines its 2% longer-run inflation goal using the annual change in the headline PCE price index rather than CPI. PCE covers a broader range of consumer spending and adjusts as households change what they buy, while CPI tracks prices for a basket of goods and services. In August, headline PCE rose 0.3% for the month and 3.4% from a year earlier, while core PCE rose 0.2% and 3.0%, respectively; the Fed reviews these readings alongside CPI to distinguish persistent price pressure from short-term food and energy swings. 5
Federal Reserve calibrates monetary policy to help lower inflation.
We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.


 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.