
Is your financial plan keeping pace?
Market and rate changes can shift your outlook. Consider a portfolio review today.
Interest rates affect bond prices and yields in opposite directions, while higher starting yields can strengthen long-term income potential.
The 2026 bond market outlook depends on Federal Reserve policy, inflation, economic growth, Treasury borrowing, and investor demand.
A diversified bond portfolio can balance income, interest-rate sensitivity, credit quality, liquidity, taxes, and an investor’s time horizon.
Bonds can generate income, preserve capital, and help offset stock market volatility within a diversified portfolio. Higher starting yields now offer investors more income potential than they had through much of the past decade. The opportunity extends beyond U.S. Treasuries, although each bond sector carries a different mix of credit risk, liquidity, and sensitivity to interest-rate changes.
A bond allocation should begin with the role it needs to play in the financial plan, not a forecast of the Federal Reserve’s next decision. Income needs, planned spending, time horizon, risk tolerance, and tax considerations help determine how much interest-rate and credit risk to accept. When those choices align with the broader portfolio, bonds can provide steadier cash flow and diversification as market expectations change.
The Federal Reserve most directly influences short-term interest rates by setting a target range for overnight bank lending. Longer-term Treasury yields also reflect expected Fed policy, but economic growth, inflation, federal borrowing, and investor demand play larger roles as maturities extend. Those forces can move short-term and long-term yields in different directions during the same market cycle.
Bond prices and yields generally move in opposite directions. When market yields rise, existing bonds with lower fixed payments become less attractive, which usually pushes their prices lower. When yields fall, existing bonds that pay more interest can gain value because investors may pay a higher price for that income.
Higher starting yields can improve a bond portfolio’s long-term income potential even when market prices fluctuate. The 10-year U.S. Treasury yielded 4.94% on October 30, 2026, after trading above 5% at points during October.1 Investors should still match maturities to expected spending because longer-term bonds usually experience larger price changes when rates move.
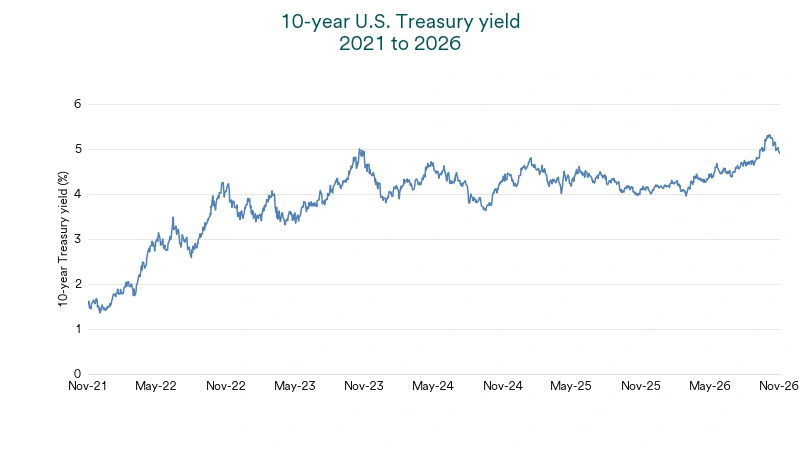
Short- and long-term bond yields respond to different combinations of monetary policy, economic growth, inflation, Treasury issuance, and investor demand. The Federal Reserve has the most direct influence on short-term rates, while the other forces become more important farther out on the yield curve. Looking at these drivers separately helps explain why yields across maturities can move in different directions.
Economic growth and inflation shape longer-term bond yields because both influence the return investors require to lend money over time. Personal Consumption Expenditures (PCE) inflation, the Fed’s preferred measure of underlying price pressure, rose from 2.8% in December 2025 to 3.8% in May 2026 and stood at 3.6% in September from a year earlier. Higher energy costs can spread through transportation, production, and consumer prices, slowing progress toward the Fed’s 2% inflation goal and keeping upward pressure on yields.
Geopolitical conflict can change the inflation outlook by disrupting energy production, shipping routes, and global supply chains. Higher oil, freight, and insurance costs can spread through transportation, manufacturing, and consumer prices, while a prolonged energy shock can also slow economic growth by redirecting household and business spending toward fuel. Bond investors may then demand higher long-term yields to offset the risk that inflation reduces the purchasing power of future interest payments, although yields can fall temporarily when investors favor Treasuries during an initial flight to quality.
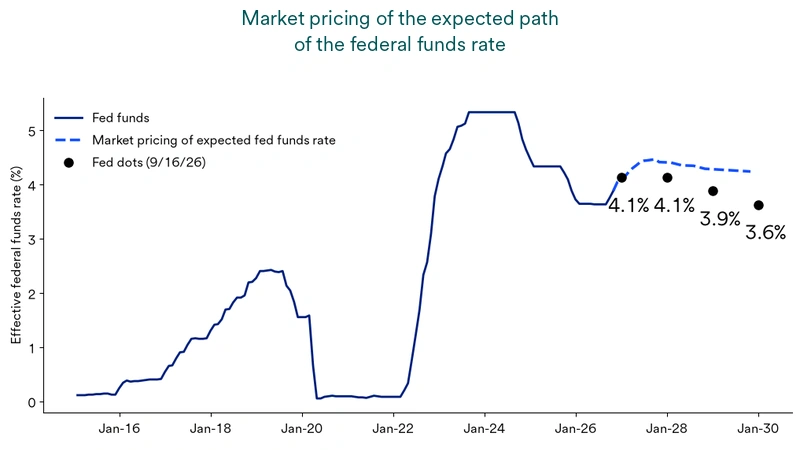
At its October 28 meeting, the Federal Open Market Committee held the federal funds target range at 3.75%–4.00% after raising it by 0.25 percentage point in September. Two voting members favored another increase, while the committee chose to gather more information on inflation and economic activity. Market pricing continued to point to another rate increase in December and two additional increases in 2027.
Fed Chair Kevin Warsh has described the 2% inflation target as essential to the central bank’s credibility. He has also questioned forward guidance, the public signals policymakers provide about future decisions, because economic conditions can change before the Fed acts. At his October press conference, Warsh emphasized returning inflation to 2% while explaining that the committee could pause to assess the September increase and incoming data.
Markets anticipate three additional rate increases over the next 12 months, including one in December 2026, as inflation and energy prices remain elevated. “Investors expect more Fed tightening, but inflation, oil prices, and labor market conditions can quickly change the path,” says Tom Hainlin, national investment strategist with U.S. Bank Asset Management Group. Investors can prepare for several outcomes by balancing short-, intermediate-, and longer-term maturities instead of relying on one policy forecast.
Federal borrowing affects bond yields because investors must absorb the Treasury securities issued to finance government spending. A larger supply can lead investors to demand higher yields, particularly when inflation or fiscal policy adds uncertainty. Those higher yields may improve income for new buyers, while reducing the market value of existing bonds.
“Over time, bond investors want federal revenue and spending to support timely principal and interest payments. That points to difficult choices about spending, taxes, or both.”
Bill Merz, head of capital markets research for U.S. Bank Asset Management Group
“Over time, bond investors want federal revenue and spending to support timely principal and interest payments,” says Bill Merz, head of capital markets research for U.S. Bank Asset Management Group. “That points to difficult choices about spending, taxes, or both.” If investors question whether federal revenue will keep pace with borrowing, they may demand higher yields to hold longer-term Treasury debt, creating additional income potential while reinforcing the value of diversification.
The yield curve compares Treasury yields across maturities, from short-term bills to long-term bonds. On October 30, 2026, the curve sloped upward, with the 10-year Treasury yielding 4.94% and the two-year Treasury yielding 4.56%. Extending maturity can provide more income in this environment, but longer-term bonds generally experience larger price swings when interest rates change.
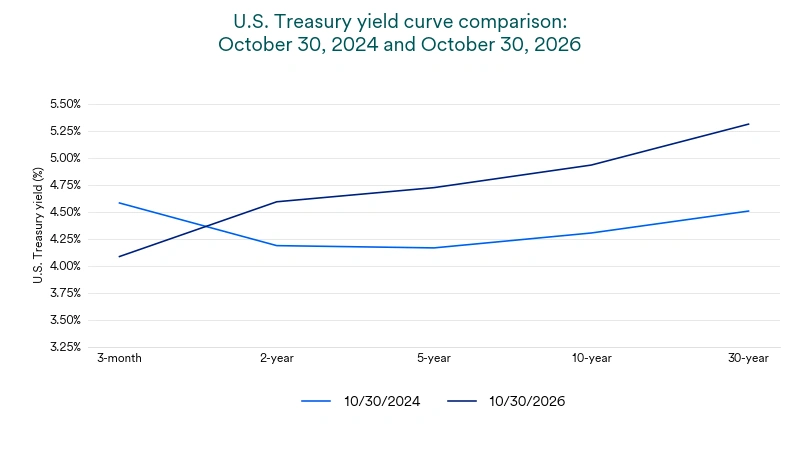
Higher yields can make bonds more attractive, but yield alone does not establish value. Investors should weigh additional income against credit quality, maturity, and liquidity, or how easily a bond can trade near its market value. This goal-based comparison can help avoid risks that offer too little compensation.
Diversification reduces dependence on any single interest-rate outcome. High-quality government and corporate bonds may emphasize stability and income, while lower-rated or less liquid holdings may offer more yield in exchange for greater risk. The appropriate mix should support cash-flow needs, tax considerations, and an investor’s comfort with price changes.
Investors can use fixed income as a toolkit rather than a single bet on the direction of interest rates. Spreading holdings across maturities and sectors can balance income, price sensitivity, and credit risk while preserving access to cash. Higher-yielding bonds deserve selective use, with credit quality, liquidity, and portfolio objective receiving as much attention as the advertised yield.
Today’s upward-sloping yield curve gives investors an opportunity to reassess bond maturity exposure. Short-term bonds may provide competitive income with smaller day-to-day price changes, while intermediate- and longer-term bonds can add income and may help diversify a portfolio if economic growth slows. The right mix depends on cash-flow needs, time horizon, tax profile, and how much portfolio volatility an investor can reasonably tolerate.
While rising interest rates offer investors the chance to earn higher yields on fixed income investments, they negatively affect existing bondholders. When interest rates increase, the prices of existing bonds drop. As a result, existing bondholders may see their total returns decrease, depending on how much interest rates rise.
The impact is more significant on those who hold longer-term bonds. Bonds with a longer duration pay a fixed amount of interest regardless of ongoing market trends. Therefore, when interest rates increase, these bonds can decrease in value more sharply. Shorter-term bonds that are maturing sooner experience less price volatility as interest rates fluctuate.
Investors in bond mutual funds should evaluate the fund’s duration as a key factor in understanding the price risk associated with the fund’s fixed income holdings. Conversely, if interest rates fall, longer-term bonds tend to be much more appealing and can increase in value more significantly than shorter-term bonds.
Bond yields mirror the market’s interest-rate expectations. When yields rise, it signals that markets expect higher interest rates, which could reflect a Federal Reserve (Fed) increase in the federal funds rate, or higher inflation or economic growth expectations. Conversely, when bond yields fall, it indicates anticipation of upcoming Fed rate cuts or slower growth and inflation.
Today’s bond market offers a meaningful income opportunity without removing the tradeoffs that come with fixed income. Attractive yields give income-focused investors more room than they had during the low-rate years, while policy uncertainty, inflation risk, and fiscal pressure still argue for diversification. Investors who align maturity, credit quality, and liquidity with broader portfolio goals can improve their chances of earning durable income without taking uncompensated risk.
Talk to your wealth professional for more information about how to position your fixed income investments consistent with your goals, investment time horizon, risk tolerance, and tax profile. A conversation can help translate rate headlines into practical choices about maturity, credit quality, and diversification.
Investments in fixed income securities are subject to various risks, including changes in interest rates, credit quality, market valuations, liquidity, prepayments, early redemption, corporate events, tax ramifications and other factors. Investments in fixed income securities typically decrease in value when interest rates rise. This risk is usually greater for longer-term securities. Investments in lower-rated and non-rated securities present a greater risk of loss to principal and interest than higher-rated securities.
The municipal bond market is volatile and can be significantly affected by adverse tax, legislative or political changes and the financial condition of the issuers of municipal securities. Interest rate increases can cause the price of a bond to decrease. Income on municipal bonds is generally free from federal taxes but may be subject to the federal alternative minimum tax (AMT), state and local taxes.
Bond yields change as investors react to economic growth, inflation trends, and Federal Reserve policy decisions. When inflation looks higher or the Fed signals tighter policy, investors often demand higher yields to hold bonds. When inflation cools or growth slows, yields can fall as investors accept a lower return in exchange for stability.
Bond prices and interest rates typically move in opposite directions. When rates rise, existing bonds with lower interest payments become less attractive, so their prices often fall; when rates fall, those existing bonds can rise in value. If you hold a bond to maturity, you generally get face value back (assuming no default), but the market price can fluctuate along the way.
Higher yields can improve the income a bond portfolio generates and raise the starting point for longer-term returns compared with low-yield periods. However, bonds can still help diversify a portfolio and support steadier cash flow even when rates are lower. Many investors focus less on timing and more on building a bond mix that matches their time horizon and comfort with price swings.
The U.S. Treasury market continues to reflect the interplay between monetary and fiscal policy, along with inflation and growth trends.
We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.

 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.