
Is your financial plan keeping pace?
Market momentum and rate changes can create new opportunities. See if your plan is ready.
The S&P 500 remains above correction territory, while the Nasdaq Composite has partially recovered after a correction tied to artificial intelligence spending, financing, and company-specific risks.
Strong earnings, consumer spending, and broader market participation continue to support stocks, but elevated inflation, bond yields, and energy costs raise the risk of further volatility.
Investors can prepare for a market correction by staying diversified, investing excess cash gradually, and confirming that portfolio risk still matches long-term financial goals.
The U.S.-based S&P 500 reached an all-time high on October 6 after advancing on strong earnings expectations despite elevated energy prices, a Federal Reserve pivot to rate hikes, and uncertainty surrounding the U.S. midterm elections. The index later fell as much as 6.0% before recovering to 3.0% below its peak on November 11, while the Nasdaq Composite recovered to 7.9% below its high after declining as much as 11.9%. The Nasdaq’s correction reflected greater pressure on technology stocks as investors reassessed artificial intelligence (AI) spending, financing, and company-specific risks.1
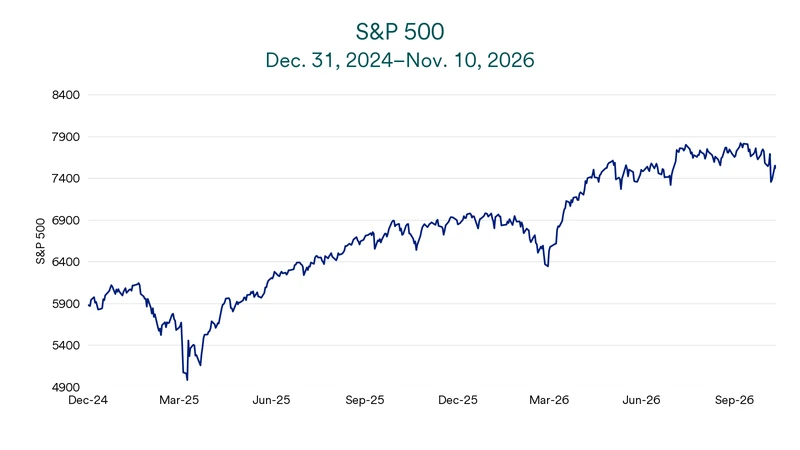
A market correction generally describes a decline of at least 10% from a recent high, while a drop of 20% or more defines a bear market. The Nasdaq Composite crossed the correction threshold during the October–November decline before recovering part of its loss, while the S&P 500 avoided a 10% decline. The uneven moves show how technology stocks face greater pressure even when the broader economy and many other stocks continue to advance.
Major headlines often move markets quickly, but the lasting effect depends on whether an event alters the trajectory of economic growth or corporate profits. Earnings, consumer demand, inflation, interest rates, energy supply, and credit conditions help show whether a pullback reflects short-term uncertainty or a more durable change in the outlook. Those indicators currently describe an economy with solid momentum but a more selective market.
Corporate earnings remain the strongest support for stock prices. Consensus estimates call for S&P 500 earnings to grow 33% in 2026 and 16% in 2027.1 That profit growth supports higher stock prices without requiring investors to pay increasingly higher valuations for the same level of earnings.
Consumer spending and business investment continue to drive revenue growth, while earlier investments in productivity have helped companies protect profit margins from higher energy and financing costs. The economy expanded at a 3.4% annualized rate in the third quarter, according to data from the Bureau of Economic Analysis, with AI investment and consumer demand contributing to the gain. Stronger productivity also gives companies more capacity to absorb cost pressures without passing every increase to customers.
Earnings strength does not eliminate correction risk, particularly when expectations are high. Companies must continue converting investment into revenue, profits, and cash flow to justify current prices. Disappointing results from major index companies would create larger market swings because the biggest stocks represent a substantial share of the S&P 500 and Nasdaq Composite. As of November 10, the top 10 stocks of the S&P 500 comprise approximately 37% of the index, while the largest 10 stocks comprise more than 56% of the Nasdaq Composite.
The 2026 rally extends well beyond the largest technology and communication services companies. Through November 10, 10 of 11 S&P 500 sectors posted positive year-to-date returns, while the equal-weighted S&P 500, which gives every company the same influence, outpaced the popular market-capitalization-weighted index. Mid-cap and small-cap stocks also advanced, showing that gains reached companies well beyond the largest index members.1
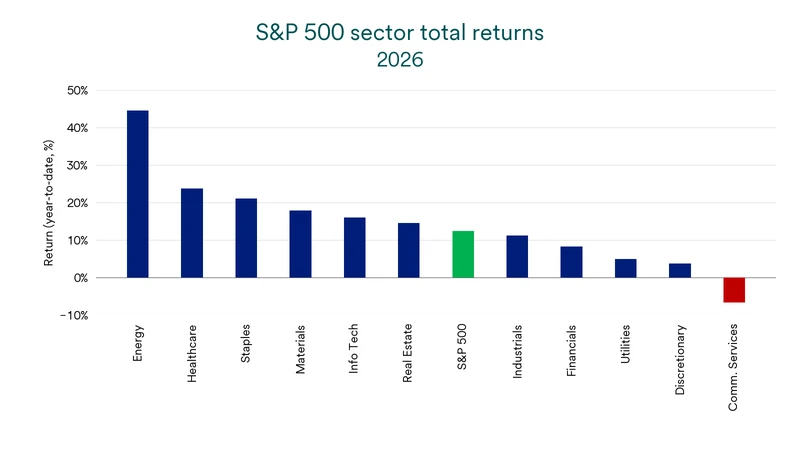
International stocks added another source of return. Developed-market stocks represented by the MSCI EAFE Index and emerging-market stocks represented by the MSCI Emerging Markets Index both posted positive year-to-date results through November 10.1 Broader gains across sectors, company sizes, and regions reduce the market’s dependence on one narrow technology trade.
“Markets tend to be more resilient when leadership broadens because performance does not depend on one sector or region going right,” says Rob Haworth, senior investment strategy director for U.S. Bank Asset Management Group. “Recent strength in the average stock has helped offset weakness among several large technology companies.” That rotation supports the broader market even as the Nasdaq Composite works through a correction.
Household spending continues to generate company revenue, although financial conditions vary widely across consumers. Higher-income households sustain much of the growth in travel, dining, and other discretionary purchases, while many middle-income consumers remain selective and lower-income households face greater pressure from food, fuel, and borrowing costs. This uneven foundation supports near-term profits, but it leaves demand more vulnerable to weaker income growth or another increase in essential expenses.
October employment data pointed to continued economic momentum. Employers added 165,000 jobs, the unemployment rate fell to 4.1%, and weekly jobless claims reached their lowest level since 1969, according to the Bureau of Labor Statistics.2 Low layoffs, wage growth, and improving productivity support household income and spending, although investors should watch whether hiring and purchasing power remain strong enough to sustain demand in 2027.
“Consumer spending and business investment continue to support revenue growth, while productivity gains have helped companies protect profit margins,” says Terry Sandven, chief equity strategist for U.S. Bank Asset Management Group. “Companies have converted those strengths into unusually strong profit growth.” Incoming results will show whether that performance holds as interest and energy costs remain elevated.
Artificial intelligence remains a powerful source of business investment, but investors have raised the standard for companies tied to the theme. Large technology companies with extensive cloud and data center networks, sometimes called hyperscalers, continue buying advanced chips, servers, networking equipment, and power capacity. These outlays create revenue for semiconductor companies, utilities, industrial businesses, data center operators, and other firms across the AI supply chain.
Recent volatility reflects questions about how companies will finance this buildout, how quickly customers will adopt AI tools, and whether new products will strengthen core businesses. Competition among chip designers and cloud providers can also shift market leadership, even if total AI spending continues to grow. Company-specific controversies, including scrutiny surrounding NVIDIA’s chief executive, can amplify moves because NVIDIA holds an unusually large weight in major indexes and investor portfolios.
The distinction for investors is between a durable investment cycle and the near-term returns of individual companies. AI spending may continue supporting economic growth even as selected stocks decline while valuations and expectations reset. A broader market correction becomes more likely when weaker AI investment reduces orders, hiring, power demand, and earnings across the wider economy.
Inflation pressures stocks by reducing household purchasing power, raising company costs, and limiting profit margins. The Personal Consumption Expenditures Price Index, the Federal Reserve’s preferred inflation measure, rose 3.6% from a year earlier in September, while the measure excluding food and energy increased 3.1%.1 Both remain above the Fed’s 2% goal, leaving policymakers less flexibility to support markets by lowering interest rates.
The Federal Reserve has shifted from early-year expectations of rate cuts to actual and anticipated rate increases. Higher policy rates raise borrowing costs, while higher longer-term bond yields make bonds more competitive with stocks and reduce the value investors assign to future corporate profits. Markets have absorbed higher rates amidst the quick earnings rise, but a simultaneous increase in yields and decline in earnings expectations would create a more difficult backdrop.
Energy prices connect the Iran conflict with inflation, interest rates, and stock market risk. Shipping constraints remain in place, but inventory releases, added production, alternate transportation routes, and shifts in demand continue to cushion the loss of supply. A prolonged disruption that overwhelms those offsets would lift household and business costs, keep the Fed restrictive, and weaken corporate profits at the same time.
The market axiom that “bull markets do not die of old age” directs attention to the forces that can end them. Corrections usually begin when investors lower expectations for economic growth, earnings, or the value of future profits. Aggressive rate increases, an earnings recession, an inflation shock, extreme valuations, or an external event each pose correction risk, but the effect on the economy and corporate profits determines whether the setback remains temporary or develops into a bear market.
“Corrections usually occur when risks move from potential to economic reality. Corporate earnings and economic growth have outweighed recent risks, but markets will respond if higher costs, tighter financing, or weaker demand begin to alter that foundation.”
Bill Merz, head of capital markets research for U.S. Bank Asset Management Group
Credit stress offers one example of that transmission. Missed debt payments, the failure of a large borrower, or trouble at a financial institution often prompt lenders to charge more interest, limit new loans, or refuse to refinance existing debt. Households and businesses then tend to cut spending and investment, weakening company revenue and profits and leading investors to demand lower stock prices as compensation for greater risk.
Policy changes after the 2026 midterm elections add another source of uncertainty. Negotiations over government funding, defense, healthcare, financial regulation, and AI policy will shape business investment, household demand, inflation, interest rates, and corporate earnings. New restrictions on data center development or AI financing would pressure selected companies, while broader economic damage would require policy changes that materially reduce investment, demand, or access to capital.
“Corrections usually occur when risks move from potential to economic reality,” says Bill Merz, head of capital markets research for U.S. Bank Asset Management Group. “Corporate earnings and economic growth have outweighed recent risks, but markets will respond if higher costs, tighter financing, or weaker demand begin to alter that foundation.” Investors should watch the interaction among yields, credit conditions, earnings estimates, and market breadth rather than rely on a single warning sign.
Periods of volatility test discipline more often than they require a new investment strategy. Investors should start by confirming that stock, bond, cash, and alternative allocations still align with long-term goals and with their ability to tolerate losses. Strong market gains sometimes shift a portfolio away from its intended risk level, making periodic rebalancing more useful than reacting to each headline.
Investors holding excess cash can reduce the pressure of choosing a perfect entry point by putting money to work gradually on a predetermined schedule, a practice known as dollar-cost averaging. Diversification across U.S. and international stocks, company sizes, high-quality bonds, and other suitable assets reduces reliance on one market outcome. Higher bond yields also provide more income and potential portfolio stability than investors earned through much of the past decade.
“Volatility creates uncertainty, but it does not eliminate the value of a long-term plan,” says Tom Hainlin, national investment strategist with U.S. Bank Asset Management Group. “Staying invested and diversified, then making measured adjustments when conditions or personal circumstances change, keeps the portfolio connected to its purpose.” A wealth planning professional helps distinguish temporary market noise from developments that alter the long-term outlook and confirms that your investment strategy still aligns with your time horizon, risk appetite, and financial goals.
A market correction usually refers to a decline of about 10% to less than 20% from a recent high, while larger declines are often described as bear markets. Corrections can occur even when the economy is growing and often reflect shifting expectations rather than lasting damage. They are a normal part of market cycles.
Historically, the S&P 500 has experienced average intra-year declines of roughly 14% since 1990, even as long-term returns have remained positive.1 That history shows why pullbacks can occur during otherwise strong years. Understanding this pattern can help investors keep perspective when prices move quickly.
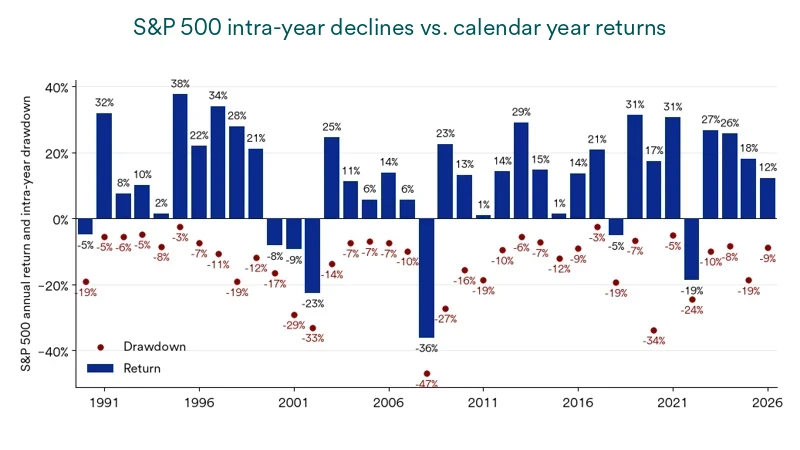
Market corrections can last days, weeks, or months, and timelines vary because different catalysts unwind at different speeds. The average correction (10% to 20% decline) lasts 17 days, but any single episode can run shorter or longer depending on whether the decline reflects temporary shifts in expectations or deeper economic stress.1 Recoveries also vary because markets often price in new information before it shows up in slower-moving economic data.
Corrections occur often enough that long-term investors generally treat them as part of the market’s regular rhythm rather than as rare events. The S&P 500 has spent 29% of its history since 1927 trading 10% or more below a recent high, which shows that double-digit pullbacks have been common over time.1 That history does not predict the next move, but it helps investors frame volatility as a recurring feature of markets.
Key indicators of a market correction include rising market volatility, sustained increases in energy or interest rates, and growing uncertainty around economic growth or corporate earnings. Corrections become more likely when higher costs or tighter borrowing conditions start to affect consumer spending or business investment. Short-term headlines alone rarely drive sustained declines; lasting changes in economic conditions usually carry more weight.
Many investors start by separating time horizons. Short-term moves can look dramatic, while long-term plans often assume periodic pullbacks along the way. Diversification can help because different investments may respond differently to growth, inflation, and interest-rate shifts, which reduces reliance on a single outcome.
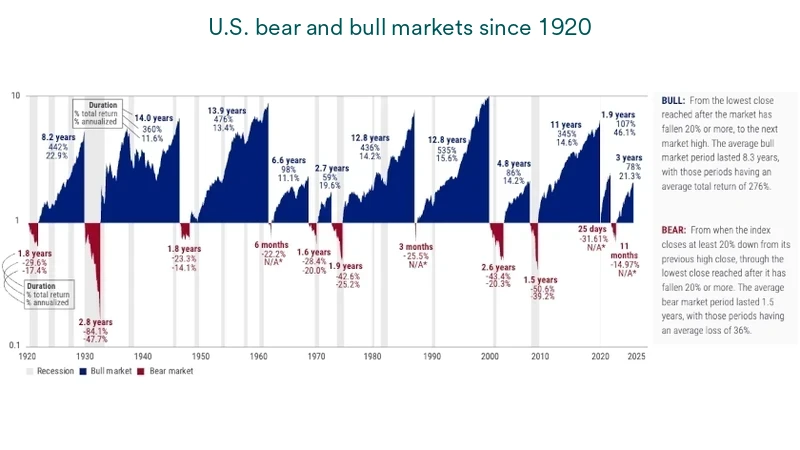
Yes, stock market corrections can occur even when the economy is strong. Corrections often follow changes in investor expectations, starting valuations, or external shocks such as geopolitical conflict or government policies. Strong economic indicators can support the broader outlook, but they do not prevent periods of market volatility.
Changing interest rates can influence market corrections by changing borrowing costs and how investors value future profits. When interest rates rise, borrowing often becomes more expensive, which can slow economic activity and pressure stock prices as expectations adjust. When interest rates fall, financing typically becomes cheaper, which can support spending and investment and may soften or delay a correction.
Typical warning signs leading to a pullback in the stock market include stretched stock prices, rising interest rates, and increasing economic uncertainty. Additional indicators can include weakening corporate earnings, unusually one-sided positioning, or heightened geopolitical instability. Investors often watch for when these risks start to show up in real activity, such as slower spending or tighter credit, rather than relying on headlines alone.
The S&P 500 Index consists of 500 widely traded stocks that are considered to represent the performance of the U.S. stock market in general. Equity securities are subject to stock market fluctuations that occur in response to economic and business developments. Diversification and asset allocation do not guarantee returns or protect against losses.
Discover how the stock market is impacted by the policies enacted during President Trump’s second term in the White House.

We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.
 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.