
Capitalize on today's evolving market dynamics.
With changes to taxes and interest rates, it's a good time to meet with a wealth advisor.
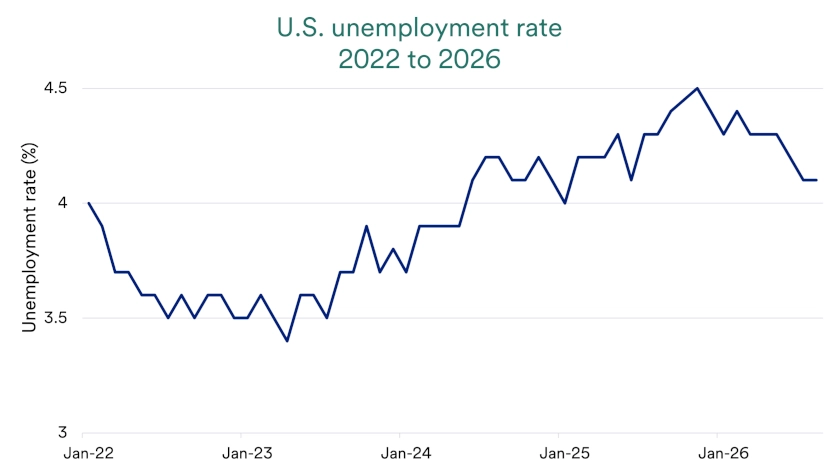
The August jobs report strengthened the U.S. job market, with 162,000 new payrolls and unemployment holding at 4.1%.
Labor market data show limited layoffs and fewer job changes, while slower wage growth challenges household purchasing power.
The jobs market gives the Federal Reserve room to focus on inflation before its September interest-rate decision.
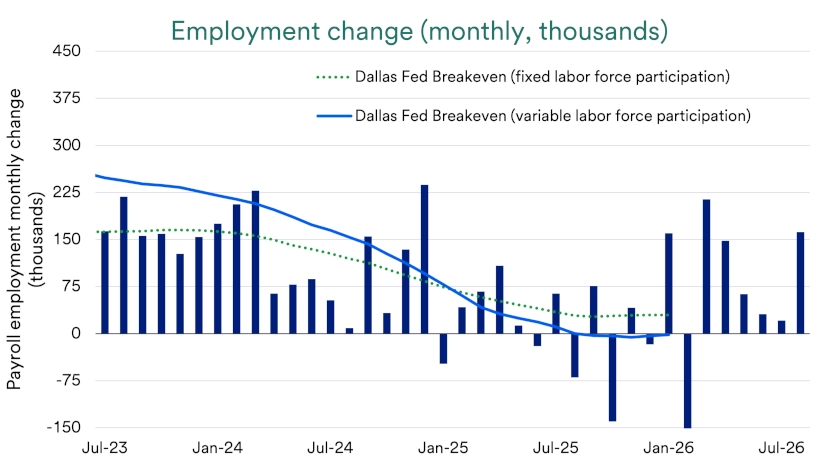
The August jobs report showed renewed hiring after a weak start to the summer, while the broader U.S. labor market continued to grow at a restrained pace. Employers added 162,000 jobs in August, and the unemployment rate held at 4.1%, according to the Bureau of Labor Statistics (BLS). The gain improved the near-term labor market picture without establishing a faster hiring trend.
Revisions strengthened the previous two months, lifting June payroll growth to 31,000 and changing July from an initially reported loss of 23,000 jobs to a gain of 21,000. Employers added an average of about 71,000 jobs per month from June through August. Labor force participation edged up to 61.6% in August, though it is still 0.5 percentage point below January’s level.
Employment and wage growth support household income, and confidence in future paychecks helps consumers spend what they earn. Consumer spending accounts for more than two-thirds of U.S. economic activity, connecting labor conditions directly to the broader economic outlook. The Federal Reserve also considers maximum employment alongside stable prices when deciding the appropriate level of short-term policy interest rates.
“The August report gives the Federal Reserve more room to focus on inflation. Payroll growth recovered, unemployment remained low and layoffs stayed contained. Policymakers will still evaluate the full trend, including wage growth and new inflation data, before deciding whether the economy needs a change in interest rates.”
Bill Merz, head of capital markets research for U.S. Bank Asset Management Group
Slowing workforce growth means the economy does not need the same number of new jobs each month to keep the unemployment rate stable. The Federal Reserve Bank of Dallas defines “break-even” employment growth as the monthly job gain needed to maintain a steady unemployment rate. In their March 2026 paper, they assert slower immigration and lower labor force participation have reduced that threshold. August payroll growth exceeded recent break-even estimates, but the three-month average still points to restrained labor market growth. 1
The labor market continues to support household spending, despite slowing income growth. Through August, Johnson Redbook and Fiserv data showed year-over-year spending growth between 7–10%, showing no consumer spending pullback despite weaker summer hiring. Stable employment can sustain purchases, though fewer job opportunities may encourage more household savings and delay discretionary spending.
Average hourly earnings rose 3.1% from a year earlier in August, while the Consumer Price Index increased 3.4% in the 12 months through July. Prices therefore rose slightly faster than wages over those periods, limiting gains in household purchasing power. Wage growth that consistently exceeds inflation would give consumers more room to increase spending without depleting savings, adding debt or relying on asset price appreciation to fund purchases.
“The August jobs report improved the near-term labor market picture, but one stronger month does not erase the slower underlying trend,” says Rob Haworth, senior investment strategy director with U.S. Bank Asset Management Group. “Low unemployment and limited layoffs continue to support household spending. Payroll growth, labor supply and wage gains together will show whether employment can sustain August’s momentum.”
The BLS Job Openings and Labor Turnover Survey, known as JOLTS, reported 7.3 million job openings and 5.1 million hires in July. Quits held at 3.1 million, and the quits rate remained near historical averages at 1.9%. Because workers often leave voluntarily when they see better opportunities elsewhere, a rising quits rate would point to higher worker confidence in the labor market.
Layoffs and discharges held at 1.7 million in July, with the layoff rate unchanged at 1.0%. These figures describe a low-hiring, low-layoff labor market rather than one marked by widespread workforce reductions. Employers appear selective about adding workers but generally reluctant to cut existing staff.
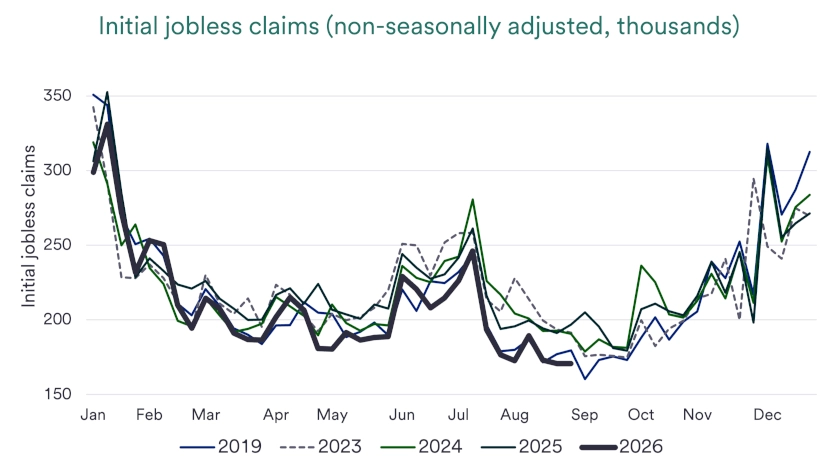
Weekly unemployment claims provide a timely check on whether layoffs are growing. Initial claims totaled a seasonally adjusted 206,000 for the week ended August 29, near historically low levels. Continuing claims reached 1.78 million for the week ended August 22. The low level of new claims indicates that most employers continue to retain workers, although some displaced workers need more time to find another position.
Announced job cuts increased in August but remained below last year’s level. Challenger, Gray & Christmas reported 52,881 planned cuts, below historical averages and marking the lowest August total since 2022, despite rising 58% from July. Together with weekly claims and JOLTS layoffs, the data point to targeted restructuring rather than broad labor market stress.
The Federal Reserve considers maximum employment and stable prices when setting short-term interest rate policy. August’s stronger payroll growth and low unemployment reduce the urgency to support the economy with lower rates, while inflation above the Fed’s 2% long-term goal reinforces the case for higher rates. Slower wage growth and modest average hiring keep the outlook balanced rather than pointing decisively toward higher or lower rates.
“The August report gives the Federal Reserve more room to focus on inflation,” says Bill Merz, head of capital markets research for U.S. Bank Asset Management Group. “Payroll growth recovered, unemployment remained low and layoffs stayed contained. Policymakers will still evaluate the full trend, including wage growth and new inflation data, before deciding whether the economy needs a change in interest rates.”
The Federal Reserve held the federal funds target rate at 3.50% to 3.75% on July 29, with three policymakers preferring a quarter-point increase. The Federal Open Market Committee will announce its next rate decision on September 16 after reviewing the August jobs report and new inflation data. Bond yields and interest rate expectations may remain sensitive to each new reading on employment, wages and prices.
The latest data support a balanced investment view. August’s hiring rebound, low unemployment and limited layoffs support consumer spending, while slower wage growth and modest average payroll gains leave the economy with less protection from future shocks. The next several reports will show whether August began a firmer hiring trend or represented a temporary improvement.
“Investors should recognize the improvement in August without treating one report as a complete economic signal,” says Tom Hainlin, national investment strategist with U.S. Bank Asset Management Group. “A low-layoff economy can continue to expand with moderate hiring, but wage growth must outpace inflation to strengthen household purchasing power. We are watching whether job creation remains broad and whether inflation continues to moderate.”
A diversified portfolio can help investors navigate moderate growth, persistent inflation and changing interest rate expectations. High-quality bonds may offer income and diversification, while company earnings and financial strength remain important when evaluating stocks across industries. If you are weighing how job market trends affect your investment plan, consider working with a financial professional to align portfolio decisions with your goals, time horizon and risk tolerance.
The labor market is a major driver of economic health in an economy where consumer spending makes up more than two-thirds of economic activity, according to the U.S. Bureau of Economic Analysis. When employment is high, consumer incomes are usually rising, supporting consumer confidence and typically leading to increased spending on goods and services. This accelerated spending often leads employers to add workers to satisfy growing goods and services demand. While the economy can experience periods of slower growth, the long-term trend is an expanding economy, which results in long-term job and income growth.
A strong employment environment often boosts incomes, which often drives rising consumer spending. When individuals are employed and earning solid wages, healthier economic growth often follows. Full-time employment provides households with predictable cash flow, making it easier to make long-term commitments that require financing, such as home and auto purchases.
Structural changes tied to fundamental shifts that affect how work is done often influence labor market trends. For instance, in the past, there was a structural shift from agricultural work to factory work as society became more industrialized. More recently, technology advances sparked an upturn in jobs tied to technology, or jobs that use technology to complete tasks. Today, many economists expect artificial intelligence (AI) advances to again create structural labor market changes and expand productivity. This could affect the types of jobs available and labor supply trends.
Labor force participation, a measure of the share of the population working or actively seeking work, has declined from its previous peaks. This decline is due in large part to workforce demographics, specifically the nation’s aging population and immigration changes. According to U.S. Bureau of Labor Statistics data, the labor force participation rate peaked at 67.2% in 2001 and now stands below 62%. Nearly one-quarter of the nation’s workforce is age 55 or older, and the “exit rate” due to retirement outpaces the entry rate of younger generations.
Technological advancements often create anxiety about the labor market impact. Technology and job requirements are constantly changing. Recent artificial intelligence advancements make this issue even more topical. In previous periods, technological advancements often involved automation replacing certain physical tasks. Today, AI may augment cognitive tasks, possibly changing skill demand in the economy.
Labor market signals can be a guide to current or forthcoming economic conditions. In other situations, labor data may not provide clear guidance. For example, when job growth appears strong, the numbers could be deceptive because hiring may be concentrated in narrow sectors of the economy or in less productive roles. If unemployment remains steady but hiring numbers are sluggish, it could indicate that companies are “hoarding” employees if it becomes challenging to replace them, while adding few new hires.
Investors should assess hiring and layoff data together, rather than in isolation. Rising layoffs may raise alarms. Low layoff rates may reflect companies’ reluctance to lose staff or indicate a challenging hiring environment. Hiring numbers and job openings reflect labor demand, but they may be lower even in a solid economic environment if companies retain staff and take a more cautious approach to adding overhead. The quits rate is a strong barometer of worker sentiment. A high quits rate reflects worker confidence that other jobs are readily available.
The job market is a key economic indicator, but investors should consider it alongside other indicators. The labor market and inflation are closely connected. If wages rise considerably, it’s important to assess that increase on an after-inflation basis to determine how much workers benefit from the wage environment, which translates to spending growth potential. Strong employment numbers typically signal a healthy economy.
The job market connects people looking for work with employers searching for talent. A strong job market signals a healthy, growing economy, as companies add jobs and compete for workers. When unemployment rises and job growth slows or declines, it often points to an economy that’s losing momentum.
The U.S. Bureau of Labor Statistics tracks the unemployment rate every month, giving us a clear view of the nation’s economic health. A lower unemployment rate usually means the economy is strong. This rate draws close attention because it shows how many people are actively seeking work. However, it doesn’t count those who have stopped looking or consider themselves out of the workforce.
When unemployment rises, it signals that the economy may be weakening. People often cut back on spending if they worry about losing their jobs, which can slow the economy even more. On the other hand, low unemployment typically reflects a robust and expanding economy.
The S&P 500’s recent rollercoaster performance has investors wondering what lies ahead for the stock market.
We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.


 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.