
Is your financial plan keeping pace?
Market and rate changes can shift your outlook. Consider a portfolio review today.

Election results, changing policy expectations, and renewed scrutiny of AI investment have added to market volatility, reinforcing the value of reviewing a financial plan rather than reacting to each headline.
Review whether your mix of stocks, bonds, cash, and other investments still fits your goals, time horizon, liquidity needs, and ability to absorb losses.
Use rebalancing, diversification, and a phased plan for excess cash to keep long-term investment decisions grounded in your financial plan.
Investors regularly face a wall of worries, from geopolitical conflict and shifting trade policy to inflation, interest-rate uncertainty, and questions about the durability of economic growth. Recent election results have added to policy uncertainty, while investors have intensified their scrutiny of the demand and profitability supporting artificial intelligence (AI) investment. Each concern affects markets differently, giving investors a timely reason to confirm that their portfolios still align with their goals, time horizon, liquidity needs, and tolerance for periodic market declines.
A conversation with a financial advisor turns market uncertainty into a practical review of your plan. Rather than trying to predict the next headline or the market’s exact low point, ask whether your mix of stocks, bonds, cash, and other investments still fits your goals, time horizon, liquidity needs, and ability to absorb losses. As Rob Haworth, senior investment strategy director for U.S. Bank Asset Management Group, explains, “A portfolio cannot anticipate every turn in the daily news cycle, so evaluate new developments within the broader economic and market trend.”
Market gains and losses change how much of your portfolio sits in stocks, bonds, cash, and other investments even when you make no trades. After an extended rise in stocks, your equity allocation sometimes exceeds its target and exposes you to more volatility than your plan anticipated. Rebalancing restores the intended mix by trimming positions that have grown beyond their targets and adding to areas that have fallen below them.
Volatility often exposes the difference between the risk an investor expects to tolerate and the losses the investor is financially equipped to absorb. An appropriate risk level reflects both your willingness to endure market swings and your financial ability to stay invested without disrupting near-term spending or long-term goals. Tom Hainlin, national investment strategist for U.S. Bank Asset Management Group, puts the response in practical terms: “Staying invested, maintaining diversification, and making measured adjustments keeps a portfolio aligned with the outcomes an investor is trying to achieve.”
Cash and cash-like investments should cover planned spending, emergencies, and other needs that should not depend on favorable market conditions. Income stability, upcoming expenses, and the structure of your financial plan determine the appropriate amount, although many households begin with an emergency reserve equal to three to six months of essential expenses. Separating necessary liquidity from long-term investment capital helps avoid selling assets during a downturn while limiting the long-run cost of holding more cash than your plan requires.
Concentration often builds quietly when a small group of stocks, one sector, or one region outperforms the rest of the portfolio. Diversification across U.S. and international markets, company sizes, bonds, and other suitable investments reduces reliance on a single source of return because growth, inflation, and interest-rate changes affect each area differently. Ask your advisor where the portfolio carries its largest overlapping exposures and whether those positions still serve a deliberate role.
Rising oil prices pressure household budgets, business costs, and inflation when supply disruptions persist. Bill Merz, head of capital markets research for U.S. Bank Asset Management Group, explains, “Investors watch energy prices because sustained increases reach well beyond the gas pump, affecting personal budgets, company margins, and the path of interest rates.” Instead of trading on each move in oil prices, assess whether higher costs have begun to alter spending, earnings, or the assumptions behind your financial plan.
Extra cash offers reassurance when headlines turn negative, but waiting for an obvious all-clear signal often leaves investors on the sidelines during the early stages of a recovery. Dollar-cost averaging, or investing equal amounts on a predetermined schedule, reduces the pressure of choosing one entry point and makes the plan easier to follow. This approach does not guarantee a profit or prevent losses, but it provides a disciplined path for moving long-term capital into a diversified portfolio.
Volatility changes relative prices and creates opportunities outside the holdings that led the previous advance. A portfolio review helps identify a useful role for international equities, smaller companies, infrastructure, high-quality bonds, or other assets that respond differently to economic growth, inflation, and interest rates. Rather than add investments simply because they have fallen, broaden the portfolio with exposures that fit your objectives and improve its balance.
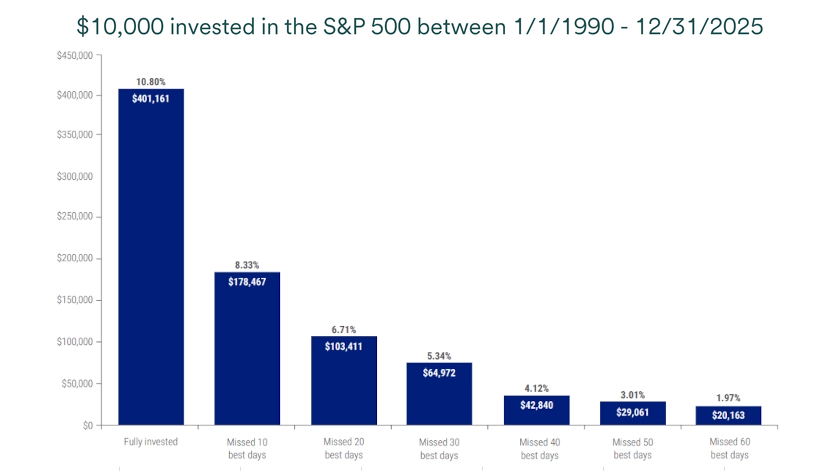
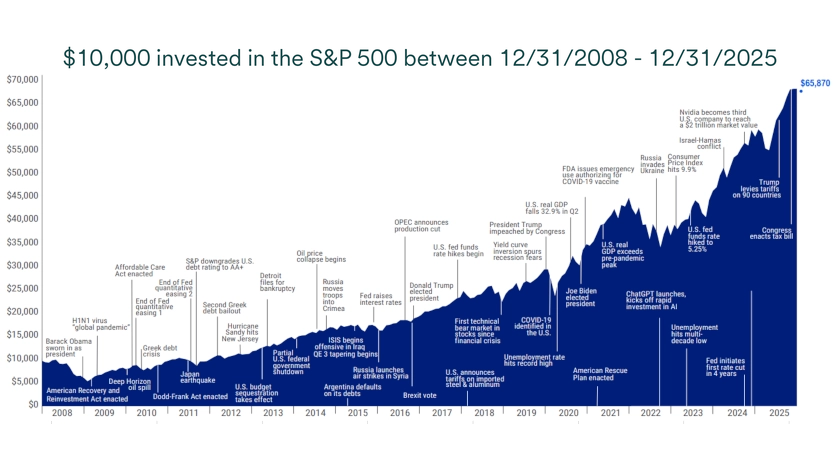
Market history shows that investors often pay a price for reacting to fear. Missing the market’s strongest days has had a major effect on long-term returns, and stocks have often finished years with gains even after meaningful declines during the year. That does not mean investors should ignore risk. Instead, they are often better served by reviewing all elements of their plan carefully than by making an all-or-nothing shift based on one event.
“A portfolio cannot anticipate every turn in the daily news cycle, so evaluate new developments within the broader economic and market trend.”
Rob Haworth, senior investment strategy director for U.S. Bank Asset Management Group
It also helps to identify the forces supporting markets beneath the headlines. Terry Sandven, chief equity strategist for U.S. Bank Asset Management Group, says, “Consumer spending and business investment continue to support revenue growth, while productivity gains have helped companies protect profit margins and generate strong earnings.” Those strengths do not eliminate the risk of another decline, but they explain why investors should weigh current volatility against the direction of economic growth and corporate profits.
Investors should also watch whether energy prices, inflation, and interest rates begin to weaken that foundation. Sandven explains, “Inflation pressures stock valuations when higher costs squeeze household purchasing power and company profits, especially if persistent price increases lead the Federal Reserve to raise interest rates.” A balanced portfolio and a disciplined review process address those risks without turning one period of volatility into an all-or-nothing investment decision.
Not necessarily. Election results, policy shifts, geopolitical conflict, and questions about artificial intelligence investment affect markets in different ways, but short-term volatility does not automatically require a change to your long-term strategy. Review whether these developments alter your goals, cash needs, time horizon, or ability to take risk before making a major portfolio shift.
Recent market moves make rebalancing appropriate when allocations have moved meaningfully away from their targets. Rebalancing offers a rules-based response by reducing positions that exceed their intended weights and adding to areas that now fall short. Your advisor should also consider taxes, transaction costs, and near-term cash needs when deciding how quickly to restore the portfolio’s target mix.
First, separate money reserved for emergencies and planned spending from capital intended for long-term growth. Cash needed in the next several months serves a different purpose from funds intended to remain unspent for years, and treating both pools the same leaves too much of the portfolio exposed to inflation and missed market gains. If the balance exceeds your liquidity target, work with your advisor on a phased investment schedule and a diversified destination for each installment.
Diversification and asset allocation do not guarantee returns or protect against losses. Past performance is no guarantee of future results.
A fresh look at managing cash and investments in today’s changing interest rate environment can help support your pursuit of the goals that matter most to you.
We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.

 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.