
Is your financial plan keeping pace?
Market momentum and rate changes can create new opportunities. See if your plan is ready.
Democrats won control of Congress in the 2026 election, changing the policy outlook but not providing a reliable stock market signal.
U.S. stocks gained an average of 12.4% in the 12 months after midterm elections, but economic conditions varied widely across election cycles.
Investors can respond by assessing how enacted policies may affect growth, inflation, interest rates, and earnings while keeping portfolios aligned with long-term goals.
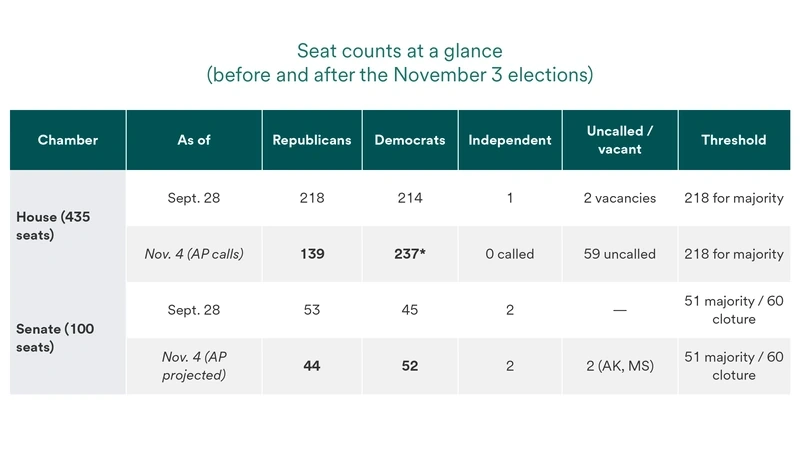
Democrats won control of the House and Senate in the November 3, 2026 midterm elections, ending unified Republican control for the final two years of President Donald Trump’s second term. Several races remain unresolved, but Democrats secured the majorities needed to control both chambers. The result creates divided government in Washington.
Republicans entered the election with narrow majorities in both chambers. The table below compares that pre-election balance with Associated Press race calls available on November 4. The results show the shift from unified Republican control to a Democratic Congress.
Affordability ran through many of the election results as voters weighed gasoline prices, mortgage rates, tariffs, and everyday costs. Democrats also gained a net five governorships previously held by Republicans. At the state and local level, voters approved 33 measures that restrict data-center development, reflecting concern about electricity demand, utility costs, and the effect of large projects on local communities.
A Democratic Congress and a Republican president will need to negotiate over government funding, the debt ceiling, and defense spending. Democratic control of congressional committees also expands the party’s authority to conduct oversight and shape debate on healthcare, financial regulation, artificial intelligence, and consumer protection. A December 11 funding deadline gives lawmakers little time to reach major agreements before the new Congress takes office.
The 2026 results change the prospects for tax, spending, trade, and regulatory proposals. Major legislation will require negotiations between a Democratic Congress and Republican administration, while the administration can still pursue some changes through executive agencies. The policies that ultimately take effect can influence economic growth, inflation, interest rates, and corporate earnings, which have shown stronger historical relationships with market returns than election outcomes alone.
Investors should evaluate tax or spending measures by tracing their potential effects on growth, business costs, and corporate earnings, rather than focusing only on the party advancing them. Trade and regulatory policies can also influence household demand, investment, and financing conditions, with different effects across industries and companies. Democrats cannot enact their full agenda while President Trump remains in office, but control of Congress gives them leverage over legislation that requires bipartisan support.
The election could reach portfolios through three main channels: data-center development, industry policy, and federal borrowing. Enacted legislation, administrative action, and corporate responses will determine the size and duration of those effects. Investors can use the initial market reaction to identify changing expectations, then test those expectations against subsequent policy and economic data.
The gubernatorial and ballot results show that resistance to data-center development has broadened beyond isolated local disputes. The 33 restrictive measures will not end the artificial intelligence infrastructure buildout because demand for computing power and electricity continues to grow. They could, however, slow approvals, raise project costs, and favor companies or regions that can add capacity without shifting excessive costs to households.
Healthcare providers, health insurers, and renewable-energy companies could benefit from greater attention to traditional Democratic priorities. Pharmaceutical manufacturers may face more oversight, while negotiations could restrain defense spending or slow parts of the data-center buildout. Investors should follow the details because legislation and regulation, not broad party labels, will determine which companies benefit or face pressure.
Divided government may limit federal spending and slow the growth of government borrowing. A smaller supply of Treasury debt can support bond prices and put downward pressure on yields, the income return investors receive from bonds. Treasury yields moved modestly lower after the election, while gold rose and oil declined, but one trading session does not establish a durable trend.
Fiscal policy could also influence the Federal Reserve’s path. Slower federal spending or a more gradual data-center buildout could temper growth and inflation pressure, reducing the need for as many rate increases as markets expect. Inflation, energy prices, and incoming economic data will still guide Fed decisions, and changes in interest rates will affect industries and companies differently.
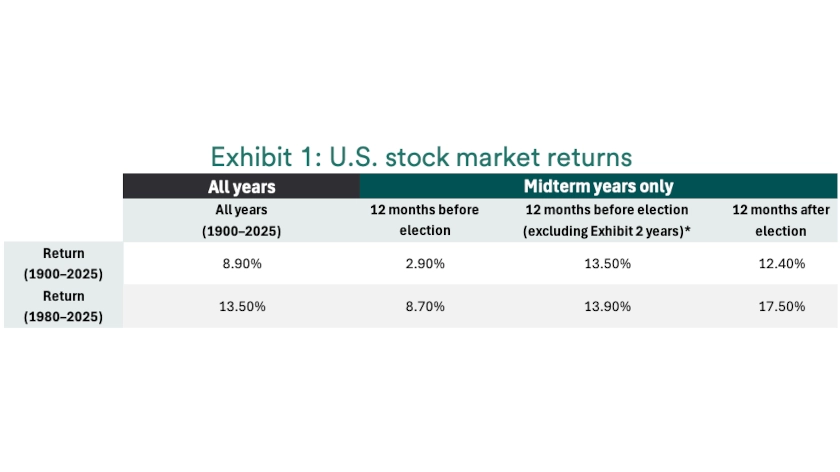
U.S. Bank Asset Management Group Research reviewed Bloomberg market data covering 31 midterm elections from 1900 through 2025. The research compared U.S. stock returns before and after each election and considered the economic, business, and geopolitical conditions surrounding those periods. The results provide historical perspective, not a forecast based on the 2026 outcome.
During the 12 months before midterm elections, U.S. stocks returned an average of 2.9%, compared with 8.9% across all years in the research. The series uses the Dow Jones Industrial Average through 1928 and the S&P 500 from 1929 onward. In the 12 months before the 2026 election, the S&P 500 delivered a 12.1% total return, well above the historical pre-midterm average.
The pre-election pattern does not provide a reliable signal to buy or sell stocks. Markets often adjust to expected policy changes before Election Day, and those expectations can shift as campaigns and economic conditions evolve. Growth, inflation, interest rates, and corporate earnings usually offer more useful information about the return outlook.
Stock market performance after midterm elections has historically exceeded the pre-election average. U.S. stocks returned an average of 12.4% during the following 12 months, while the average for elections since 1980 reached 17.5%. Greater policy clarity may help investors refocus on the economy and corporate earnings, but those conditions continue to shape returns after the votes are counted.
Stocks did not rise after every midterm, and the averages do not guarantee gains after the 2026 election. Economic and market conditions differed across each cycle. Investors can use the historical results to frame expectations while basing portfolio decisions on current conditions and long-term goals.
Economic and geopolitical events explain many of the weakest results around midterm elections. Eleven of the 31 election periods coincided with inflation shocks, rising interest rates, the Great Depression, war, financial stress, or deteriorating business conditions. Those forces affected business activity and corporate profits, making it difficult to attribute the returns to election results alone.
The economy remains the primary engine of market returns. Elections can influence fiscal policy and regulation, but the economic backdrop often determines how markets respond.
Economic growth and inflation trends have historically shown stronger relationships with market returns than election outcomes. Policy still plays a role because taxes, spending, trade, and regulation can influence demand, costs, investment, and financing. Investors can assess that connection by following employment, consumer spending, inflation, interest rates, and corporate earnings.
Statistical testing did not find differences large or consistent enough to establish a dependable midterm-election effect. A t-test assesses whether a difference between groups likely reflects a recurring pattern rather than random variation, and this test did not show that midterms consistently changed returns.1 The sample includes only 31 elections, with outcomes ranging from losses greater than 30% to gains near 50%.
The historical record becomes more useful when investors examine the conditions around each election. The Great Depression shaped 1930, while inflation and rising interest rates weighed on 1966, 1970, and 2022. Stagflation, a combination of weak growth and high inflation, drove the 1974 decline, and the collapse of the technology-stock bubble shaped 2002.
Eleven midterm years with weak stock returns, grouped by the non-election catalyst that drove them. Returns cover U.S. large-cap stocks in the 12 months leading up to each election.
Inflation and rate hikes
1946 -10.9% 1966 -13.2% 1970 -14.4% 1990 -7.5% 2022 -14.6%
Returns cover the 12 months before each election
Rising prices and tighter Federal Reserve policy raised financing costs and compressed valuations. The 1990 decline also reflected the Savings & Loan crisis and high oil prices after Iraq invaded Kuwait.
Stagflation
1974 -31.8%
Returns cover the 12 months before each election
Weak economic growth combined with high inflation, pressuring corporate profits and investor confidence in the study’s steepest decline.
Economic depression
1930 -29.9%
Returns cover the 12 months before each election
The Great Depression drove a collapse in business activity, employment and earnings.
Sentiment and valuation reversals
1962 -17.6% 2002 -15.1%
Returns cover the 12 months before each election
Faltering investor sentiment pulled prices lower in 1962 despite no single economic shock. In 2002, the technology-stock bubble burst and unwound valuations built on outsized growth expectations.
War and policy shocks
1910 -14.3% 1914 -8.8%
Returns cover the 12 months before each election
The Sherman Antitrust Act reshaped business conditions in 1910. In 1914, British investors sold U.S. assets to fund the war effort and the New York Stock Exchange closed for four months.
Growth and inflation trends provide another way to assess the historical record. Average three-month S&P 500 returns differed when growth or inflation rose or fell, and each comparison below met the research’s threshold for statistical significance. These figures describe returns observed during economic conditions, not returns caused by a midterm election.
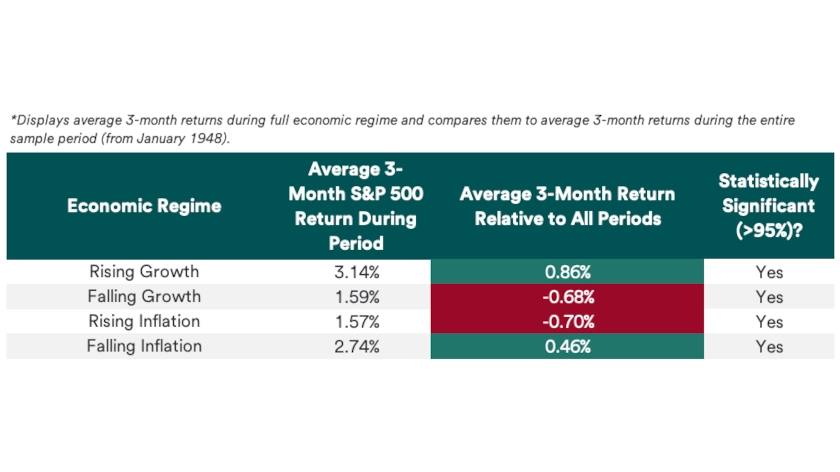
Historical patterns require context before they can inform an investment outlook. Every election occurs amid a different mix of growth, inflation, interest rates, and valuations. Investors should evaluate the economic setting and the policies that influence it instead of relying on the election calendar alone.
U.S. Bank Asset Management Group Research also compared average three-month S&P 500 returns under different combinations of White House and congressional control beginning in January 1948. The comparison covers each full period of political control, not only the months around midterm elections. Average returns reached 2.42% under one-party control and 2.17% under mixed control, but neither overall difference was statistically significant.
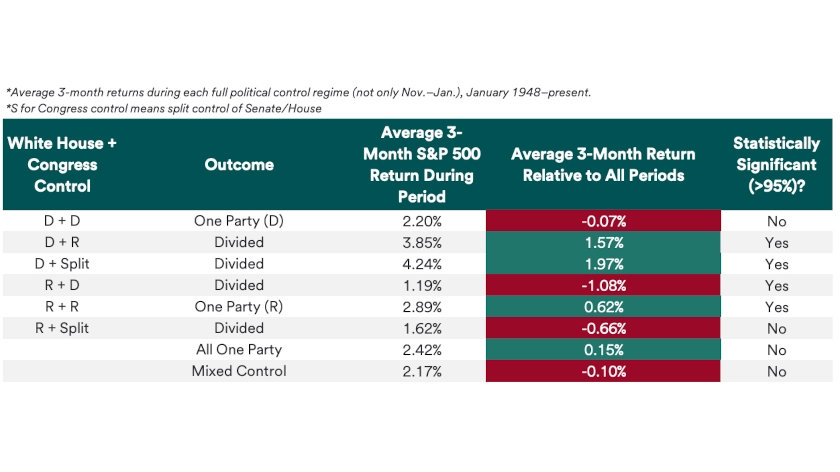
Returns varied across individual political configurations, and some differed from the average across all periods. A Republican president with a Democratic Congress, the outcome produced by the 2026 election, generated an average three-month return of 1.19%, 1.08 percentage points below the all-period average. That history does not establish causation or predict the next market move, but it reinforces the need to evaluate the economic and policy backdrop.
The election changes the path for policy and the inputs investors use to assess the outlook. Investors can trace enacted policies through their effects on growth, inflation, interest rates, and corporate earnings, then weigh those effects against valuations and portfolio goals. Consumer spending, business investment, and corporate profits continue to support a constructive outlook for diversified portfolios.
Higher-quality bonds, issued by borrowers with stronger fundamentals, continue to offer meaningful income and could benefit if growth and long-term interest rates moderate. Within equities, changes in yields, Federal Reserve expectations, and industry fundamentals can shift market leadership. Ten of the 11 S&P 500 sectors remained positive through November 4, although returns varied widely.
Companies with durable demand, sound finances, and stock prices supported by earnings and growth prospects may prove more resilient as policy and economic conditions change. Diversification and portfolio risk aligned with an investor’s time horizon can reduce reliance on a single election outcome, interest-rate forecast, or investment theme. A wealth management professional can assess whether changes in tax, spending, trade, or regulation warrant adjustments within an existing allocation. Stay informed with the latest market news impacting investors.
This information represents the opinion of Wealth Management of U.S. Bank and U.S. Bancorp Investments. The views are subject to change at any time based on market or other conditions and are current as of the date indicated on the materials. This is not intended to be a forecast of future events or guarantee of future results. It is not intended to provide specific advice or to be construed as an offering of securities or recommendation to invest. Not for use as a primary basis of investment decisions. Not to be construed to meet the needs of any particular investor. Not a representation or solicitation or an offer to sell/buy any security. Investors should consult with their investment professional for advice concerning their unique situation. The factual information provided has been obtained from sources believed to be reliable but is not guaranteed as to accuracy or completeness. Any organizations mentioned in this commentary are not affiliated or associated with U.S. Bank or U.S. Bancorp Investments in any way.
What the 2026 midterm results could mean for interest rates, industry sectors and investor portfolios.
We can partner with you to design an investment strategy that aligns with your goals and is able to weather all types of market cycles.
 Equal Housing Lender. Deposit products are offered by U.S. Bank National Association. Member FDIC. Mortgage, Home Equity and Credit products are offered by U.S. Bank National Association. Loan approval is subject to credit approval and program guidelines. Not all loan programs are available in all states for all loan amounts. Interest rates and program terms are subject to change without notice.