Why softer data haven't settled the debate
Recent U.S. economic reports have helped ease concerns about the need for additional monetary restraint. Inflation readings have generally moderated, while job growth has slowed from the pickup seen earlier this spring. Taken at face value, those developments suggest the economy is moving closer to balance.
Yet policymakers remain reluctant to draw firm conclusions. Part of the challenge is that the same data can support very different interpretations. Slower job growth, for example, would traditionally be viewed as a sign that demand is cooling. However, if hiring is slowing because the supply of labor is slowing, labor market moderation may provide less disinflationary relief than expected.
Inflation presents a similar challenge. Progress toward lower inflation has continued, but service-sector inflation remains elevated. At the same time, geopolitical developments, commodity markets, and global trade tensions remain potential sources of renewed supply-side pressure.
“The data have become less worrisome, but not necessarily more conclusive,” says Schoeppner. “Policymakers are still trying to determine whether inflation is fading because underlying imbalances are easing, or because temporary factors are masking pressures that could reemerge later.”
As a result, Fed policymakers appear increasingly focused not just on whether inflation is moving in the right direction, but also on how confidently they can explain why. Many central bankers around the world appear to be wrestling with similar questions. Recent data may have reduced the urgency for additional tightening, but they have not necessarily eliminated the possibility that further restraint may ultimately be needed.
A similar debate around the world
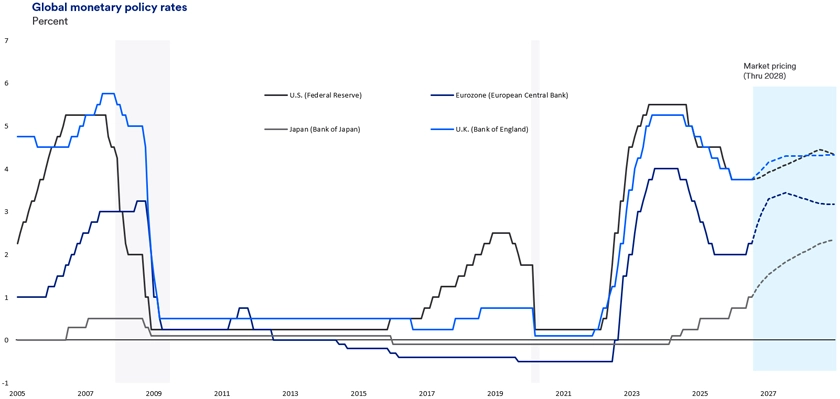
The United States is hardly alone in confronting these questions. While economic conditions differ across regions, many central banks appear to be grappling with a similar challenge of determining whether recent improvements in inflation reflect durable progress toward price stability or simply a temporary easing of pressures.
In Europe, policymakers have become increasingly data-dependent as inflation gradually moderates. The European Central Bank (ECB) continues to debate whether underlying price pressures, wage growth, and energy-related risks have eased enough to ensure inflation returns sustainably to target.
The Bank of England (BOE) faces a comparable dilemma. Inflation has improved, yet officials remain cautious about declaring victory too soon. Service-sector inflation and labor market dynamics continue to receive close scrutiny as policymakers assess whether policy is sufficiently restrictive.
Japan presents a somewhat different situation. After decades of low inflation and ultra-low interest rates, the Bank of Japan (BOJ) continues its gradual process of policy normalization. Yet even there, questions surrounding labor shortages, wage growth, and the economy’s long-run productive capacity have become increasingly important.
Despite these differences, a common theme has emerged across global monetary policy. “The challenge facing central banks today is not simply determining where inflation is headed,” says Bovino. “It's determining how much policy restraint is truly necessary to return inflation to target.” As global price pressures gradually moderate, the central question is no longer whether inflation is falling, but how much policy restraint will ultimately be required to finish the job.