What to look for in a kids savings account
How to budget for child care costs
10-min. read
Match money lessons to your child’s age, from handling coins as a preschooler to managing a first debit card as a teen.
Research shows that habits such as planning and waiting for a reward are largely shaped by age seven.
You don’t need to be a financial expert. Simple, everyday conversations can help your child build money skills.
Use grocery shopping, bill payments and family trip planning to teach earning, saving and spending.
Teach kids about money with simple lessons that fit their age. Early education about money is important as money habits like planning and waiting to spend are formed before age eight. You can start with earning, saving and spending lessons. Then build toward budgeting, allowances, financial goals and banking tools as your child grows.
Understand why early money lessons matter
Teach age-appropriate money concepts
Set up an allowance system that works
Use the three-jar budgeting method
Teach the difference between needs and wants
Help kids set savings goals and practice delayed gratification
Use everyday moments as teaching opportunities
Early money lessons can shape your child’s financial future. Studies show that many money habits form in the first seven years of life and can affect how children manage money as adults. Learning basic skills early can help kids avoid common mistakes and build financial stability.
Money skills help children manage money and make good choices. They include saving for a goal and following a budget. The Consumer Financial Protection Bureau says children need knowledge, habits and decision-making skills to support their financial well-being as adults.
Luckily, you don’t need to be a money expert to teach these skills. Grocery shopping, paying bills and planning a family trip can become simple lessons about earning, saving and spending. Letting kids help with small money choices also shows that managing money is a normal part of life.
The key is consistency. Talk about saving and spending often, celebrate small wins and include children in simple money decisions. Regular practice builds confidence and makes money feel less confusing as they grow.
|
Age |
Focus |
Recommended activities |
|---|---|---|
|
Ages 3 to 5 |
Introduce the basics |
Handle, name, sort and count coins and bills; use a clear savings jar; play pretend store; introduce needs versus wants. |
|
Ages 6 to 12 |
Build budgeting and earning skills |
Tie allowance to age-appropriate chores; manage a regular allowance; set specific savings goals; teach that money is limited. |
|
Ages 13 to 18 |
Introduce banking and credit |
Open a teen checking or savings account; discuss borrowing and credit scores; use digital banking tools; practice weighing spending trade-offs. |
Young children can start by learning what money is and how it works. Explain that things cost money and that people use money to pay for them. At this age, hands-on activities work best.
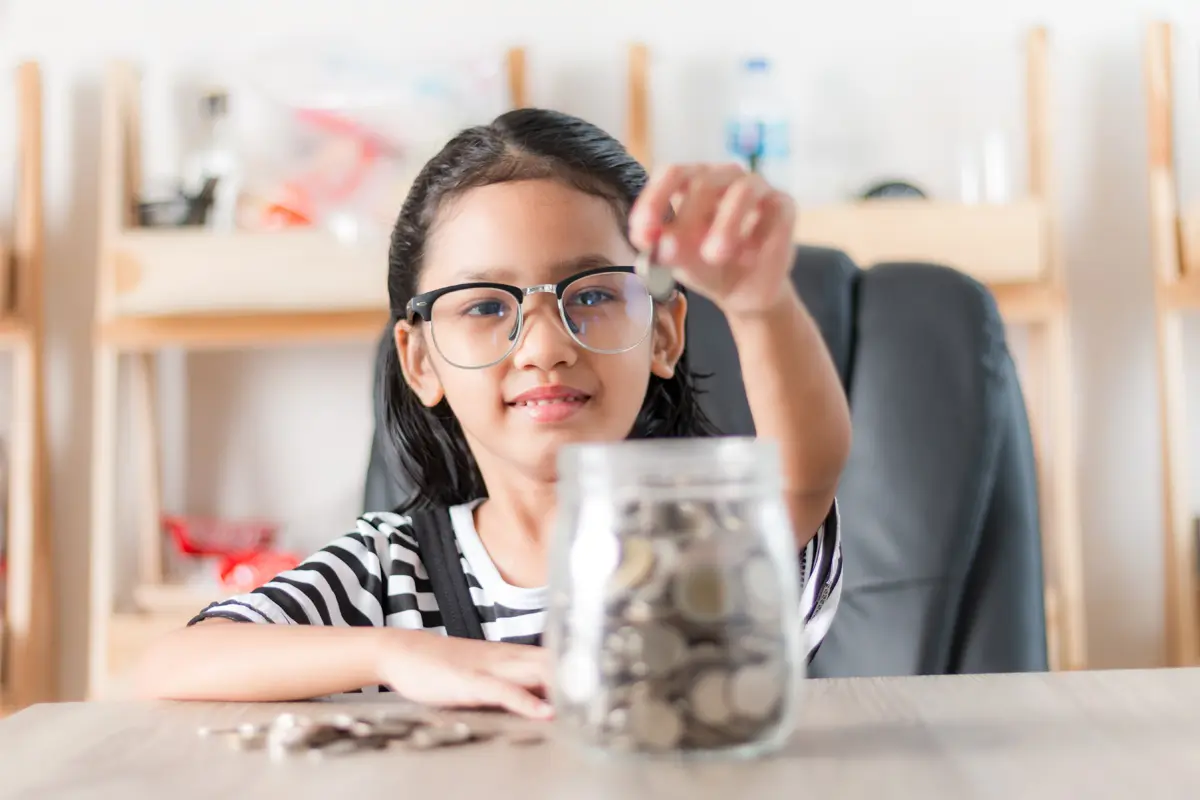
Let your child handle real coins and bills. Name each one, sort coins by size and color and count them aloud together. Use a clear jar for savings so your child can see the money grow.
You can also play “pretend store” at home with play money. This activity can teach how to buy and pay in a fun, low-pressure way.
Introduce needs and wants with simple examples. Food is a need because we must have it. Candy is a want because we can live without it.
Children in elementary school can learn more complex money ideas and take on small financial tasks. This is a good time to decide whether to give your child an allowance and how it will work.
At this stage, focus on four key skills:
Tying an allowance to age-appropriate chores can teach that money is earned through work. A regular allowance also gives children a set amount to manage, helping them practice basic budgeting and understand that money is limited.
Help your child choose a savings goal, such as a toy, game or special outing. Saving for a specific item teaches planning and how to wait for something they want.
Teenagers are ready to use real financial tools such as debit cards and learn more advanced money skills such as saving for a goal. A teen checking or savings account can help them practice managing money with parental oversight.
This is also a good time to explain the benefits and risks of credit cards and borrowing. Teach your teen to use credit with care and explain how a good credit score can help them later.
Adding your teen as a user on your credit card (if they're mature and responsible enough to handle it) can help them learn how to track their score. And mobile banking tools like autopay can show them how to make deposits, track spending and pay bills on time.
Teens can also learn to weigh spending choices. If they spend birthday money on one item, they may not have enough for another. Learning about Gen Z money trends can help you spot gaps in their knowledge. If your teen wants to grow their money, introduce basic investing concepts and explain how investing can support long-term goals.
If your teen has a part-time job, you can also teach them about income tax. How important it can be to set money aside to take care of unforeseen expenses. And how to protect sensitive information like a Social Security number, credit or debit card pin number.
A good allowance system helps children manage money on their own. It can also teach the link between work and earnings. Families usually choose between two main approaches: a fixed allowance or an earnings-based allowance.
A fixed allowance provides the same amount on a regular schedule, whether a child completes chores or not. It teaches budgeting and gives children steady income to plan.
An earnings-based allowance pays children for specific tasks. It shows that money comes from work and can help build a strong work ethic.
Here is how the two approaches compare:
|
Approach |
Pros |
Cons |
|---|---|---|
|
Fixed allowance |
Teaches budgeting, keeps money separate from behavior and provides steady income for planning. |
Does not directly teach the link between work and pay. |
|
Earnings-based allowance |
Builds work ethic, links effort to reward and reflects how jobs work. |
May make every household task feel like a paid job. |
Whichever approach you choose, pay allowance on a regular schedule. Weekly or every other week works well because children can plan how much to spend and save. Many families use $1 to $2 for each year of age as a starting point. Adjust the amount based on your family’s budget and what the allowance needs to cover.
Don’t take allowance away as punishment. This can create negative feelings about money. Keep the system consistent and use it to teach money skills, not to control behavior.
The three-jar system divides money into spending, saving and giving. This clear, visual method helps children plan for what they want now and later. It also makes a budget easier for kids of all ages to understand.
When your child receives allowance or gift money, have them divide it among the three jars. Moving the money by hand makes each choice feel real and helps them learn to create a spending plan.
The giving jar can teach children about helping others and supporting the causes they care about. The spending jar teaches another important lesson: When it is empty, they must wait before buying something else.
Needs are things we must have to live and stay safe, such as food, clean water, clothing, shelter and health care. Wants can make life more fun or comfortable, but we can live without them. Knowing the difference helps children decide what to pay first.
The line between needs and wants is not always clear. Phones, sneakers and the latest trends may feel like needs when children face peer pressure. You can explain that adults can struggle with this choice, too. But knowing the difference is key to making smart money decisions.
With practice, kids learn that needs come first and wants are still allowed. They can cover important costs first, then choose which ‘want’ matters to them the most. This simple way of setting priorities can guide their spending choices as they grow. Here are a few ways to teach this lesson:
Give saving a target. When kids save toward a specific goal, like a toy or an outing, they learn to plan and wait. Research links delayed gratification directly to higher savings, better credit scores and lower debt in adulthood.
Try these tactics to keep your child’s motivation high:
Everyday routines are your best classroom. Grocery shopping, bill paying and trip planning all turn into low-pressure lessons with no worksheets required.
Put it into action:
Having conversations about money with your children can do something powerful over time. They make money feel less intimidating and more like a normal part of life.
Youth savings accounts and supervised banking apps give kids hands-on practice with money. These tools can help children set savings goals, plan how to reach them and learn to earn, save and spend wisely.
Digital tools and apps can also help children earn, save and spend wisely with parental supervision. Family banking apps may let parents automate allowance payments, manage chores, set spending controls and receive real-time transaction alerts.
Interactive challenges and financial literacy games can help kids and teens build money knowledge. These features make learning feel more engaging and less like a chore.
When comparing youth banking tools, look for:
U.S. Bank offers eligible U.S. Bank Smartly® Checking account clients a complimentary Greenlight debit card and money app1 for families. The tools give kids hands-on practice with real money while parents can guide spending, saving, chores and allowance.
Learn how U.S. Bank and Greenlight are helping families build money skills through practical, everyday experiences.
Teaching money skills is an ongoing journey, and consistency matters most. Pick one age-appropriate action this week: start a savings jar, talk through needs and wants or open a youth account.
Ready to take the next step? Explore youth banking options or visit a local branch to meet with a banker who can help you choose the right tools for your family.
By teaching smart spending and budgeting you’re helping your children build confidence, responsibility and healthy money habits that can last a lifetime.
Research shows children’s money habits are largely formed by age seven. Starting around age three with simple concepts, like identifying coins and understanding that things cost money, builds a strong foundation for financial confidence.
Use routine activities as teaching moments. Let children compare prices at the grocery store, pay a cashier or help plan a family budget for a vacation or special purchase.
An allowance gives children a set amount to manage and can teach budgeting. Many families use $1 to $2 per year of age as a starting point and choose either a fixed allowance or one tied to completing chores.
The 50/30/20 rule divides money among needs, wants and savings. For children, a simplified three-jar version – spending, saving and giving – teaches the same idea of assigning money a purpose.
Needs are essentials such as food, shelter, clothing and healthcare. Wants are nonessential items. Practice by sorting purchases while shopping or by categorizing pictures at home.
Core skills include understanding that money is earned through work. Also, being able to distinguish needs from wants and setting savings goals. Creating a basic budget and managing a bank account or debit card responsibly are important too.
Help them choose a specific savings goal for the item they want. Teach them how to track progress with charts or clear jars. Matching part of what they save can be incentivizing. And introducing waiting periods before they spend their savings can also strengthen delayed gratification skills. This will also help them tell the difference between impulse wants and things they need and value.
 Equal Housing Lender