Key takeaways:
Treatonomics describes spending on small, affordable luxuries during financial uncertainty. These purchases often become part of a larger story we tell ourselves about reward, accomplishment or comfort.
Consider why you are making a purchase, how to enjoy it without creating a longer-term financial drag and whether it is truly an occasional treat or has become a habit.
U.S. Bank is seeing continued increases in food delivery spending, a trend that can help frame the choices consumers make around treatonomics.
As long-term financial goals can take longer to reach, a banking leader explains how consumers are finding comfort in smaller, more attainable purchases
From a specialty coffee to a wellness splurge, small rewards can feel especially meaningful for some people during uncertain times. A recent U.S. Bank/Morning Consult survey found that as larger financial goals take longer for consumers to reach, many consumers are prioritizing more immediate, lower cost ways to support wellbeing.
Derik Farrar, head of everyday banking and borrowing, explains the rise of “treatonomics” and offers guidance on balancing everyday enjoyment with long-term financial goals.
In recent years, “treatonomics” has burst onto the financial scene. What is it and why is it gaining attention right now?
Treatonomics is a relatively new name for something that has existed for a very long time. It refers to the tendency for consumers to spend money on small, affordable luxuries during periods of financial uncertainty.
It is similar to the “lipstick effect”: when people feel less confident about their finances, they may scale back larger discretionary purchases while continuing to spend on smaller indulgences.
We all love stories, and designating something as a treat can become part of a larger story we tell ourselves about reward, accomplishment or comfort. But the reason we are eating a doughnut does not change the calorie count. The same principle applies financially: the story behind a purchase does not change its cost or the effect it may have on a budget.
The recent U.S. Bank/Morning Consult survey found that with larger financial goals taking longer to reach, many consumers are deprioritizing spending on travel and luxury goods. At the same time, 44% of U.S. adults are spending more on self-care and wellness, reflecting a shift toward prioritizing balance and well-being as finances are stretched.
For many consumers, smaller indulgent purchases can provide a sense of normalcy and enjoyment without disrupting budgets or causing added stress.
Why do small purchases feel more rewarding during uncertain times?
Financial stress can create a feeling that many aspects of life are outside our control. In fact, nearly half of Gen Z adults said they avoid checking their bank account balances, while one in four adults said they would need at least $10,000 in savings to avoid feeling financial stress according to another U.S. Bank/Morning Consult survey.
Small indulgences can provide an immediate sense of satisfaction and control. Whether it's meeting a friend for coffee, buying a favorite snack or spending a few dollars on a hobby, these purchases create positive experiences that can help reduce stress and provide something to look forward to.
When do harmless treats become a budgeting problem?
Not every indulgence is a problem. In fact, building room for enjoyment into a financial plan can make it easier to stay committed to long-term goals. The key is distinguishing between an occasional treat and a habit. Remembering your work password, for example, probably does not justify a doughnut.
The challenge arises when spending shifts from intentional to habitual or becomes a coping mechanism. Financing a small indulgence can also extend its financial impact. If you fund a “treat” by paying for it in four installments, you may still be paying for it long after the enjoyment has passed.
While a single purchase may seem insignificant, repeated spending can add up over time.
Before spending, ask yourself three questions: Why am I treating myself? Is there a way to enjoy the treat without creating a longer-term drag on my finances? Is this truly a treat, or has it become a habit?
How can you balance enjoying today with saving for tomorrow?
Start by identifying your top financial priorities, whether that is paying down debt, building an emergency fund or saving for a major milestone like buying a home. By automating savings and debt payments, you can help ensure those goals remain on track.
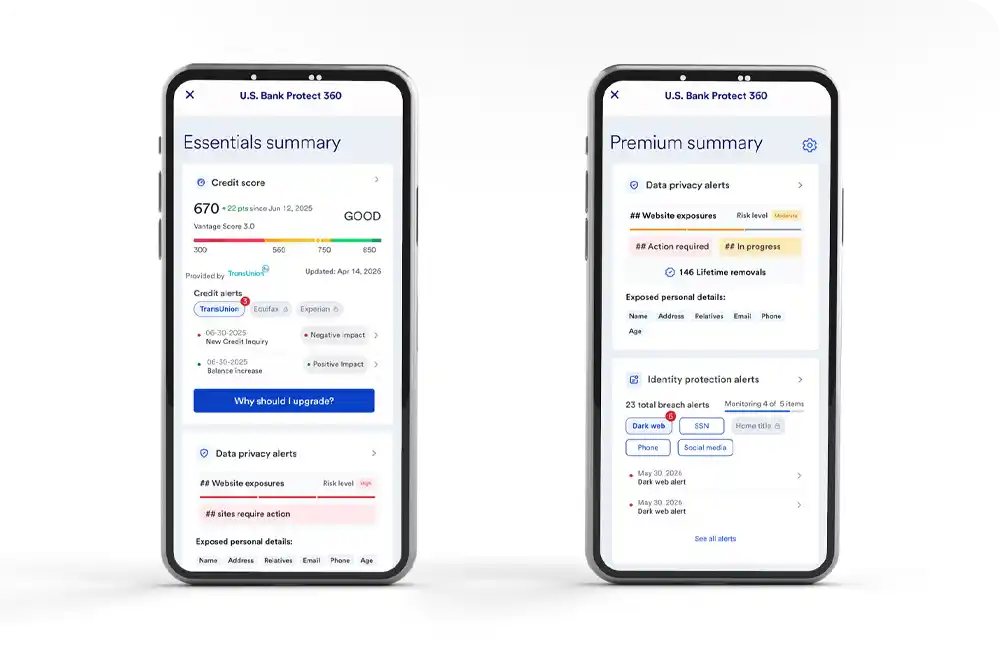
Once those priorities are covered, consider setting aside a specific amount each month for discretionary spending. Then look for ways to spend that amount more intentionally. You can also use automated tools within the U.S. Bank Mobile App to help you manage and track your spending.
Food delivery, for example, can be a productive treat in some situations. If you are celebrating with a meal, ordering food to enjoy at home may allow you to “trade up” while spending about the same amount you would at a restaurant. Everyone has to do the math for their own situation, but the goal is to make a thoughtful choice based on what matters most to you.
Successful budgeting is not about eliminating everything that brings you joy. It is about being intentional: understanding why you are treating yourself, choosing an option that does not undermine your longer-term goals and making sure an occasional reward does not quietly become a routine expense.
 Equal Housing Lender